
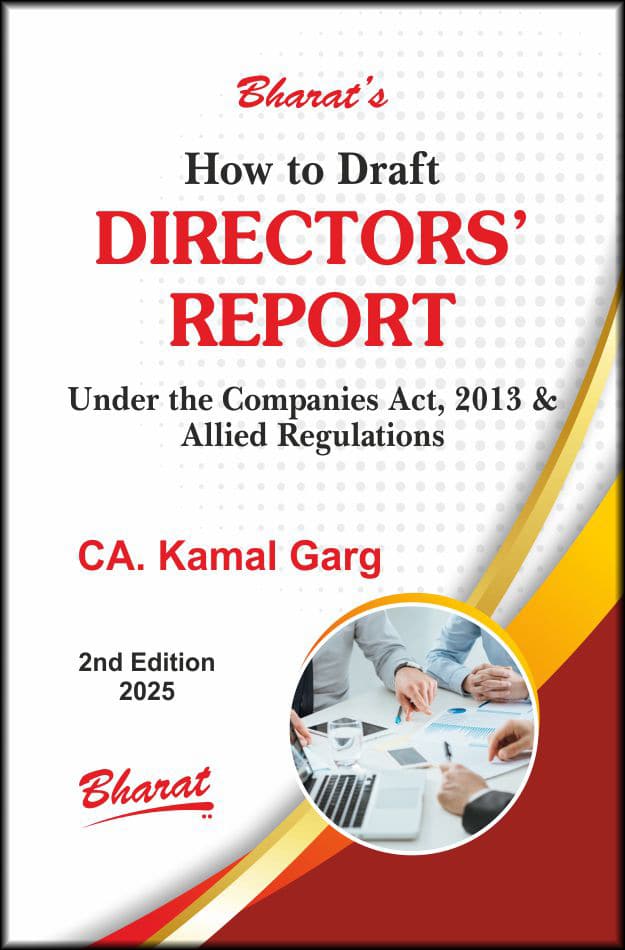
Bharat’s How to Draft DIRECTORS’ REPORT by CA. Kamal Garg
Original price was: ₹795.00.₹636.00Current price is: ₹636.00.
Bharat’s How to Draft DIRECTORS’ REPORT by CA. Kamal Garg – 2nd Edition 2025.
10 in stock
Bharat’s How to Draft DIRECTORS’ REPORT by CA. Kamal Garg – 2nd Edition 2025.
Bharat’s How to Draft DIRECTORS’ REPORT by CA. Kamal Garg – 2nd Edition 2025.
About How to Draft DIRECTORS’ REPORT
Division 1
Contents of Board’s Report
Chapter 1 Board’s Report — An Introduction
Chapter 2 Disclosures pursuant to the Companies Act, 2013
2.1. Disclosures under Section 134(3)
2.1.(a). No need to give the extract of the annual return as provided under sub-section (3) of section 92
2.1.(b). Number of meetings of the Board
2.1.(b).(i). Whether dates of Board meeting required to given
2.1.(b).(ii). Frequency of meeting – meaning of “year” thereof
2.1.(b).(iii). Practical Implications for Directors’ Report Disclosure
2.1.(c). Directors’ Responsibility Statement
2.1.(c).(i). Author’s note – avoid boilerplate language
2.1.(c).(ii). Author’s note – be careful for inconsistent accounting policies & unreasonable estimates
2.1.(c).(iii). Author’s note – accounting records for safeguarding assets and preventing fraud and other irregularities
2.1.(c).(iv). Author’s note – going concern
2.1.(c).(v). Author’s note – adequate ‘internal financial controls’
2.1.(c).(vi). Author’s note – “all” laws to be interpreted reasonably in context
2.1.(ca). Details in respect of frauds reported by auditors under sub-section (12) of section 143 other than those which are reportable to the Central Government
2.1.(d). A statement on declaration given by independent directors under sub-section (6) of section 149
2.1.(e). In case of a company covered under sub-section (1) of section 178, company’s policy on directors’ appointment and remuneration including criteria for determining qualifications, positive attributes, independence of a director and other matters provided under sub-section (3) of section 178
2.1.(f). Explanations or comments by the Board on every qualification, reservation or adverse remark or disclaimer made—
(i) by the auditor in his report; and
(ii) by the company secretary in practice in his secretarial audit report
2.1.(f).(i) Author’s Note – meaning of Auditor
2.1.(f).(ii) Author’s Note – meaning of explanation or comments
2.1.(g). Particulars of loans, guarantees or investments under section 186
2.1.(g).(i). Author’s Note – consistency in disclosure of loans, guarantees, and investments
2.1.(h). Particulars of contracts or arrangements with related parties referred to in sub-section (1) of section 188 in the prescribed form
2.1.(i). The state of the company’s affairs
2.1.(j). The amounts, if any, which it proposes to carry to any reserves
2.1.(k). The amount, if any, which it recommends should be paid by way of dividend
2.1.(l). Material changes and commitments, if any, affecting the financial position of the company which have occurred between the end of the financial year of the company to which the financial statements relate and the date of the report
2.1.(m). The conservation of energy, technology absorption, foreign exchange earnings and outgo, in such manner as may be prescribed
2.1.(m).(i). Author’s Note – missing disclosures on energy conservation, R&D, and foreign exchange when financial statements reveal what the Board’s report omits
2.1.(n). A statement indicating development and implementation of a risk management policy for the company including identification therein of elements of risk, if any, which in the opinion of the Board may threaten the existence of the company
2.1.(n).(i). Author’s Note – when the Board’s Report ignores the red flags in the financials
2.1.(o). The details about the policy developed and implemented by the company on corporate social responsibility initiatives taken during the year
2.1.(o).(i) Author’s Note – CSR disclosures: interpreting “policy developed and implemented” in light of ongoing projects
2.1.(p). In case of a listed company and every other public company having such paid-up share capital as may be prescribed, a statement indicating the manner in which formal annual evaluation of the performance of the Board, its Committees and of individual directors has been made
2.1.(q). Such other matters as may be prescribed – other than One Person Company or Small Company
2.1.(q).(i). Author’s Note – can a show cause notice be reported
2.2. Disclosures related to Employees
2.2.1 Calculation of remuneration
2.2.2 Calculation of percentage of shareholding
2.2.3 Employees’ Particulars in loose Annexure
2.3. Re-Appointment of Independent Director
2.4. Change in the composition of the Board
2.5. Disqualifications of Directors
2.6. Audit Committee – disclosures for composition and reasons for not accepting Board’s recommendation
2.7. Issue of Equity Shares with differential rights
2.8. Sweat Equity
2.9. Redemption of shares and/or debentures
2.10. Investor Education and Protection Fund
2.11. Disclosures pertaining to consolidated financial statements
2.12. Vigil Mechanism
2.13. Supplementing Disclosures
Chapter 3 Matters to be included in Board’s Report for One Person Company and Small Company
3.1. One Person Company and Small Company
3.2. Contents of the Board Report
(1) Abridged report for one person company and small company
(2) Particulars of contracts or arrangements with related parties
3.3. Qualification, reservation or adverse remark or disclaimer made by the auditor
Chapter 4 Disclosure pursuant to the Listing Regulations
4.1. Report on projection made in offer document for public or right issue by a listed company
4.2. Management Discussion and Analysis Report (MDAR)
4.3. Report on Corporate Governance
Chapter 5 Disclosure pursuant to Employee Stock Option and Employee Stock Purchase Schemes
5.1. Under Companies Act, 2013
5.2. Under SEBI Regulations
5.3. Provision of money by company for purchase of its own shares by employees or by trustees for the benefit of employees
Chapter 6 Disclosures by Producer Companies
6.1. Producer Company
6.2. Mandatory contents of the Board’s Report for a Producer Company
6.3. Application of provisions relating to private companies
6.4. Interplay between Section 134 and Section 378ZR: reconciling general and special provisions
Chapter 7 NBFCs – Disclosures Pursuant to Directions of Reserve Bank of India
7.1. Non-Banking Financial Companies
7.2. Miscellaneous Non-Banking Companies
7.3. Residuary Companies
7.4. Systemically Important Non-Deposit taking Company and Deposit taking Company
Chapter 8 Disclosures pursuant to National Housing Bank Directions
Chapter 9 Other Disclosures
9.1. Statement as to consolidated financial statements
9.2. SWOT Analysis
9.3. Projections and Estimates
9.4. Disclosures as per Secretarial Standards
9.5. Disclosure of commission to managing or whole-time director
9.6. Additional information which may be given in the Board’s Report
9.7. Dividend
9.8. Major events occurred during the year
9.9. General Information
9.10. Investor Education and Protection Fund (IEPF)
9.11. Details of Establishment of Vigil Mechanism
9.12. Auditors
9.13. Compliance with Secretarial Standards
Chapter 10 Secretarial Audit Report
Chapter 11 Cost Audit Report
11.1. Requirements of the Companies (Cost Records and Audit) Rules, 2014
11.2. Explanations in the Board’s report in response to Cost Auditors’ qualification
11.3. Reporting of frauds
Chapter 12 Explanations in the Board’s Report in response to Auditors’ Qualification
12.1. Auditors’ remarks are not available to the Board at the time of its consideration and authentication of the balance sheet and profit and loss account
12.2. Auditors’ report involves a debatable point
12.3. Meaning of Auditor
Details :
- Publisher : Bharat Law House Pvt. Ltd.
- Author : CA. Kamal Garg
- Edition : 2nd Edition 2025
- ISBN-13 : 9788119565412
- ISBN-10 : 9788119565412
- Pages : 368 pages
- Language : English
| Publisher | Bharat Law House Pvt. Ltd. |
|---|---|
| Language | English |
| Author | Kamal Garg |
Only logged in customers who have purchased this product may leave a review.
Related products
Foreign Trade Policy & Handbook of Procedures 2023 | S.C. Jain
Navigate India’s complex foreign trade regime with the updated 2nd Edition (2025) of Foreign Trade Policy and Handbook of Procedures 2023 (2 Volumes). Authored by indirect tax experts S.C. Jain, Shweta Jain, and Abhishek Jain, this comprehensive set is the ultimate reference for trade professionals.
-
✔ Complete Framework: Full text of FTP 2023, Handbook of Procedures, and the FTDR Act 1992.
-
✔ Practical Insights: Detailed coverage of incentives, exemptions (Advance Authorisation, EPCG), and export promotion schemes.
-
✔ Fully Updated: Includes the latest DGFT notifications, circulars, and allied laws impacting foreign trade (Customs, GST, FEMA).
Bharat’s Law, Practice & Procedure of GST Appeals by Dr. J.K. Mittal
Bharat's Law, Practice & Procedure of GST Appeals by Dr. J.K. Mittal - 1st Edition 2026. First, this Bharat publication provides the exact, practice-ready text on indirect tax litigation and dispute resolution in India. Specifically, written by Dr. J.K. Mittal, this definitive legal reference manual details the strict rules of managing appeal files. Furthermore, this 1st edition completely incorporates all recent operational guidelines and structural tribunal mandates running smoothly through 2026.
Bharat’s Income Tax Act, 2025 (Pocket Edn.) – 39th Edition 2026
Bharat's Income Tax Act, 2025 (Pocket Edn.) - 39th Edition 2026. First, this Bharat publication provides the exact pocket-sized legal text on direct tax laws for professionals in India. Specifically, compiled by Bharat Law House, this compact reference book details the statutory rules of the newly active Income Tax Act, 2025. Furthermore, this 39th edition includes highly useful comments and cross-reference tables updated for easy use on the go.
Taxmann’s GST on Works Contract & Other Construction/EPC Contracts by Sudipta Bhattacharjee
Taxmann's GST on Works Contract & Other Construction/EPC Contracts by Sudipta Bhattacharjee, Rishabh Prasad, Abhishek Garg - 12th Edition 2026. First, this Taxmann publication provides the exact text on engineering agreements. Specifically, the authors detail the strict rules for infrastructure taxation. Furthermore, this twelfth edition covers all fundamental 2026 legal updates perfectly.
Taxmann’s Tax Prosecution under Income-tax/GST & Black Money Laws by Gagan Kumar
Taxmann's Tax Prosecution under Income-tax/GST & Black Money Laws by Gagan Kumar - 5th Edition 2026. First, this Taxmann publication provides the exact text on criminal tax liabilities. Specifically, author Gagan Kumar details the strict rules for tax prosecution. Furthermore, this fifth edition covers all fundamental 2026 statutory frameworks perfectly.
Taxmann’s Guide to Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT) – 2nd Edition 2022
Taxmann's Guide to Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT) - 2nd Edition 2022. This book provides a comprehensive analysis of Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT). The analysis is done in light of the Income-tax Act 1961, Income-tax Rules 1962, and Relevant Case Laws. This book is amended by the Finance Act 2022.
Reviews
There are no reviews yet.