

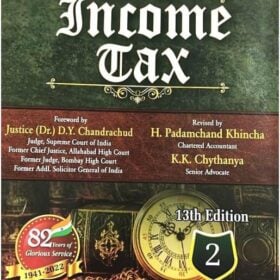
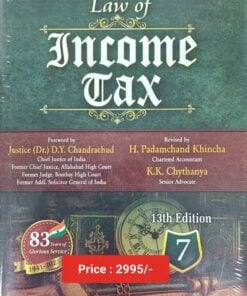
Bharat’s Law of Income Tax (Volume 1) By Sampath Iyengar – 13th Edition 2024
Original price was: ₹2,995.00.₹2,546.00Current price is: ₹2,546.00.
Bharat’s Law of Income Tax (Volume 1) By Sampath Iyengar – 13th Edition 2024.
8 in stock
Bharat’s Law of Income Tax (Volume 1) By Sampath Iyengar – 13th Edition 2024.
Bharat’s Law of Income Tax (Volume 1) By Sampath Iyengar – 13th Edition 2024.
About Law of Income Tax (Volume 1) By Sampath Iyengar
Sampath Iyengar’s Law of Income Tax has maintained its reputation as a commentary, exhaustive and encyclopedic in its sweep, and as a veritable warehouse of all the available information on the subject, besides carrying critical and in-depth comments. It is the most authentic referencer, which has stood the test of time during the last eight decades and has retained its pristine glory. This set provides not only the necessary access to all the relevant information, but also the expertise and the experience of the authors, present and past. Conflicting views are highlighted. Precedents are not merely listed, but their rationale analysed. This book has always been different in not being content with mere listing of cases, but by providing enough material to tackle any problem that may arise. No wonder it is being referred and cited as an authority at all levels of judicial interpretation – Income-tax Department, ITAT, High Courts, Supreme Court and even Authority for Advance Rulings.
While India celebrates its 75 years of Independence, Sampath Iyengar has helped the professionals, tax administrators and the judiciary for the last over 80 years in finding solutions to their tax issues. No effort is spared in the present edition to maintain the reputation, which this book has gained in the field of income-tax law for the past eight decades and more.
This locus classics has enjoyed the privilege of patronage from the profession of chartered accountants, tax practitioners, consultants, advisors, advocates, corporate executives, tax administrators and the judiciary.
Volume 1
INTRODUCTION
PRINCIPLES OF CONSTRUCTION
General Principles
Particular Principles-I
Particular Principles-II
(A) Mutuality Principle
(B) Diversion by Overriding Title
(C) Real Income Theory
(D) Concepts of Telescoping and Peak Credit
Chapter I
Preliminary
1. Short title, extent and commencement
2. Definitions
2(1)“Advance tax”
2(1A)“Agricultural income”
2(1B)“Amalgamation”
2(1C)“Additional Commissioner”
2(1D)“Additional Director”
2(2)“Annual value”
2(3)“Appellate Assistant Commissioner” (Omitted)
2(4)“Appellate Tribunal”
2(5)“Approved gratuity fund”
2(6)“Approved superannuation fund”
2(7)“Assessee”
2(7A)“Assessing Officer”
2(8)“Assessment”
2(9)“Assessment year”
2(9A)“Assistant Commissioner”
2(9B)“Assistant Director”
2(10)“Average rate of income-tax”
2(11)“Block of assets”
2(12)“Board”
2(12A)”Books or books of account”
2(13)“Business”
2(13A)“Business trust”
2(14)“Capital asset”
2(15)“Charitable purpose”
2(15A)“Chief Commissioner”
2(15B)“Child”
2(16)“Commissioner”
2(16A)“Commissioner (Appeals)”
2(17)“Company”
2(18)“Company in which the public are substantially interested”
2(19)“Co-operative society”
2(19A)“Deputy Commissioner”
2(19AA)”Demerger”
2(19AAA)”Demerged company”
2(19B)“Deputy Commissioner (Appeals)”
2(19C)”Deputy Director”
2(20)“Director”, “manager” and “managing agent”
2(21)“Director General or Director”
2(22)“Dividend”
2(22A)“Domestic company”
2(22AA)”Document”
2(22AAA)”Electoral Trust”
2(22B)“Fair market value”
2(23)“Firm”, “partner” and “partnership”
2(23A)“Foreign company”
2(23B)“Fringe benefits”
2(23C)“Hearing”
2(24)“Income”
2(25)“Income-tax Officer”
2(25A)“India”
2(26)“Indian company”
2(26A)“Infrastructure capital company”
2(26B)“Infrastructure capital fund”
2(27)“Inspecting Assistant Commissioner” (Omitted)
2(28)“Inspector of Income-tax”
2(28A)“Interest”
2(28B)“Interest on securities”
2(28BB)”Insurer”
2(28C)”Joint Commissioner”
2(28D)”Joint Director”
2(29)“Legal representative”
2(29A)“Liable to tax”
2(29AA)“Long-term capital asset”
2(29B)“Long-term capital gain”
2(29BA)“Manufacture”
2(29C)“Maximum marginal rate”
2(29D)“National Tax Tribunal”
2(30)“Non-resident”
2(31)“Person”
2(32)“Person who has a substantial interest in the company”
2(33)“Prescribed”
2(34)“Previous year”
2(34A)“Principal Chief Commissioner of Income-tax”
2(34B)“Principal Commissioner of Income-tax”
2(34C)“Principal Director of Income-tax”
2(34D)“Principal Director General of Income-tax”
2(35)“Principal officer”
2(36)“Profession”
2(36A)“Public sector company”
2(37)“Public servant”
2(37A)“Rate or rates in force” or “rates in force”
2(38)“Recognised provident fund”
2(39)“Registered firm” (Omitted)
2(40)“Regular assessment”
2(41)“Relative”
2(41A)”Resulting company”
2(42)“Resident”
2(42A)“Short-term capital asset”
2(42B)“Short-term capital gain”
2(42C)”Slump sale”
2(43)“Tax”
2(43A)“Tax credit certificate”
2(43B)“Tax Recovery Commissioner” (Omitted)
2(44)“Tax Recovery Officer”
2(45)“Total income”
2(46)“Total world income” (Omitted)
2(47)“Transfer”
2(47A)“Virtual digital asset”
2(48)“Zero Coupon Bond”
3. “Previous year” defined
SUBJECT INDEX
Details :
- Publisher : Bharat Law House Pvt. Ltd.
- Author : Sampath Iyengar Revised by H. Padamchand Khincha and Chythanya K.K
- Edition : 13th Edition 2024
- ISBN-13 :
- ISBN-10 :
- Language : English
- Binding : Hardcover
| Author | Sampath Iyengar |
|---|---|
| Language | English |
| Publisher | Bharat Law House Pvt. Ltd. |
Only logged in customers who have purchased this product may leave a review.
Related products
Foreign Trade Policy & Handbook of Procedures 2023 | S.C. Jain
Navigate India’s complex foreign trade regime with the updated 2nd Edition (2025) of Foreign Trade Policy and Handbook of Procedures 2023 (2 Volumes). Authored by indirect tax experts S.C. Jain, Shweta Jain, and Abhishek Jain, this comprehensive set is the ultimate reference for trade professionals.
-
✔ Complete Framework: Full text of FTP 2023, Handbook of Procedures, and the FTDR Act 1992.
-
✔ Practical Insights: Detailed coverage of incentives, exemptions (Advance Authorisation, EPCG), and export promotion schemes.
-
✔ Fully Updated: Includes the latest DGFT notifications, circulars, and allied laws impacting foreign trade (Customs, GST, FEMA).
Bharat’s Financial Statements of Non-Corporate Entities by CA. Kamal Garg
Bharat's Financial Statements of Non-Corporate Entities by CA. Kamal Garg - 2nd Edition 2026. First, this Bharat publication provides the exact, practice-ready text on reporting guidelines, ledger disclosures, and accounting formats for un-incorporated setups in India. Specifically, written by CA. Kamal Garg, this manual outlines the strict rules of preparing books for non-corporate setups. Furthermore, this 2nd edition incorporates all active disclosure parameters and structural compliance revisions running flawlessly through 2026.
Taxmann’s GST on Works Contract & Other Construction/EPC Contracts by Sudipta Bhattacharjee
Taxmann's GST on Works Contract & Other Construction/EPC Contracts by Sudipta Bhattacharjee, Rishabh Prasad, Abhishek Garg - 12th Edition 2026. First, this Taxmann publication provides the exact text on engineering agreements. Specifically, the authors detail the strict rules for infrastructure taxation. Furthermore, this twelfth edition covers all fundamental 2026 legal updates perfectly.
Taxmann’s MSME Digest By Mukesh Mohan Gupta
Taxmann's MSME Digest By Mukesh Mohan Gupta - 1st Edition 2026. First, the MSME Digest serves as a comprehensive legal guide. Specifically, it consolidates the evolving laws governing India's Micro, Small, and Medium Enterprises (MSME) sector. Furthermore, this practice-ready reference brings together landmark decisions from the Supreme Court and various High Courts.
Taxmann’s Income Tax Act – As Amended by Finance Act 2025
Taxmann's Income Tax Act - As Amended by Finance Act 2025 - 70th Edition 2025. This book seamlessly integrates all amendments from the Finance Act 2025 into a single authoritative text. It offers extensive annotations, cross-references, and legislative history, catering to practitioners, academics, and libraries. Separate divisions also cover the Finance Act 2025, STT, CTT, and the now-ended Equalisation Levy, ensuring a holistic overview of direct tax laws. A user-friendly layout—with marginal notes, footnotes, and a comprehensive subject index—enables efficient navigation. Backed by meticulous editorial accuracy, this volume remains a definitive guide to direct tax legislation.

Reviews
There are no reviews yet.