
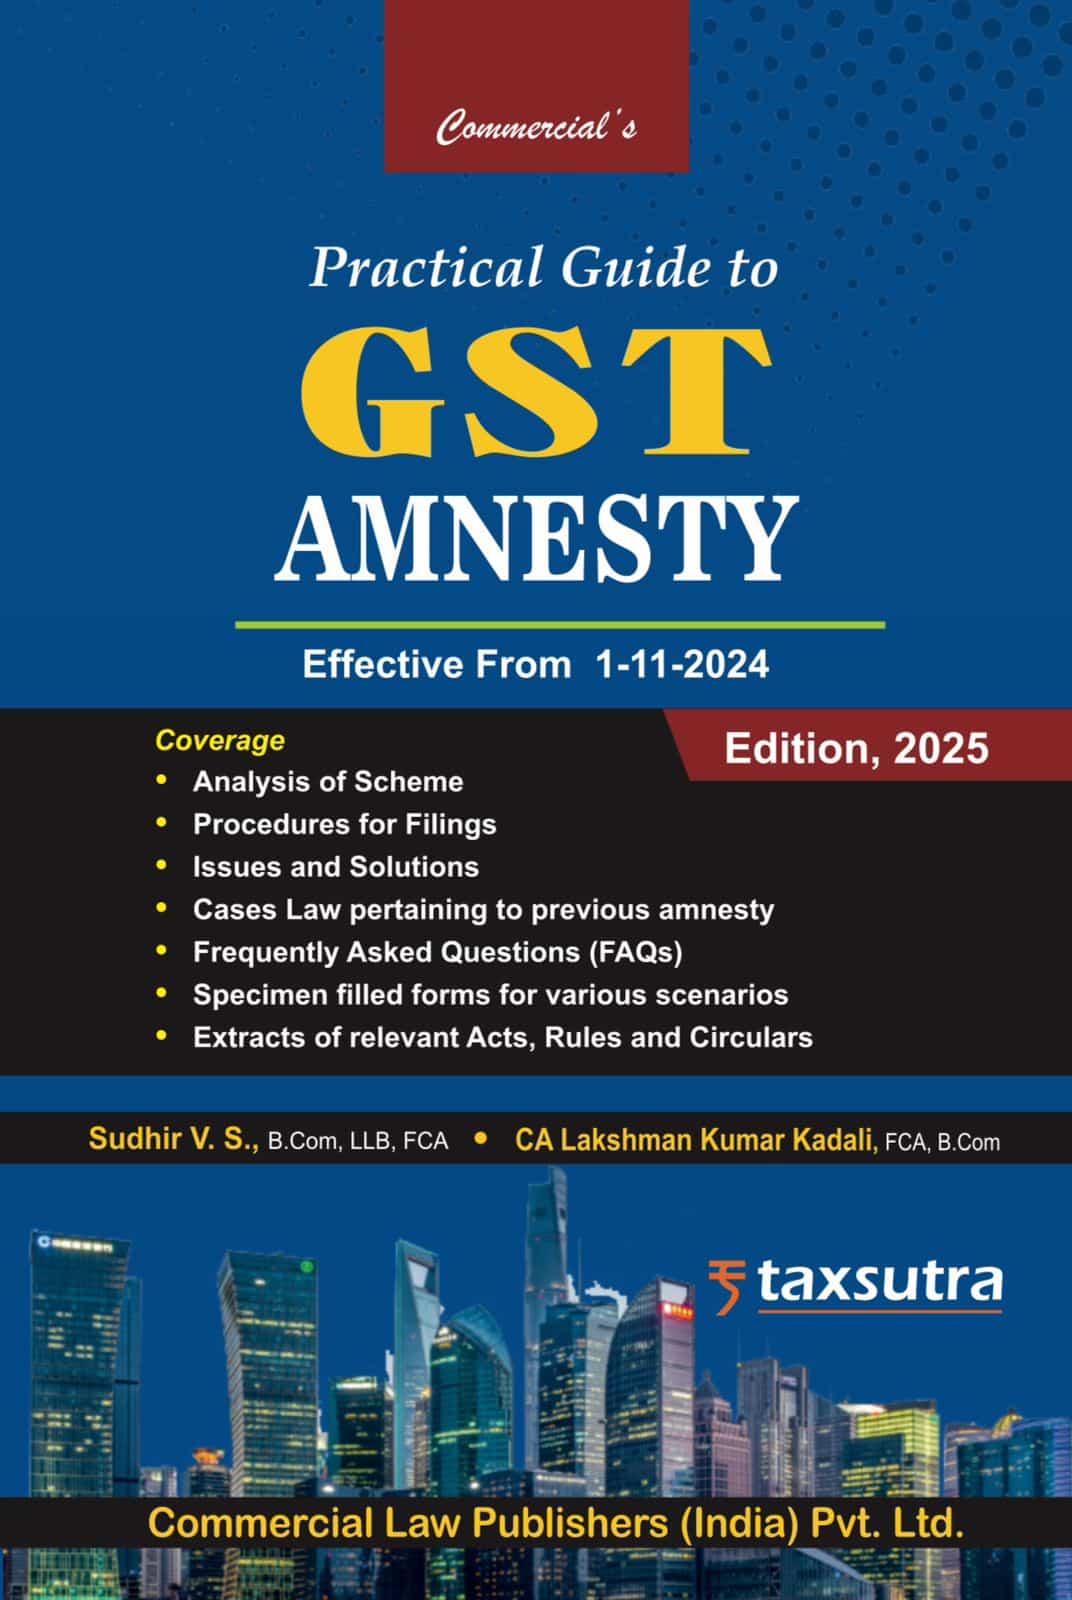
Commercial’s Practical Guide to GST Amnesty by V.S. Sudhir – 1st Edition 2025
Original price was: ₹695.00.₹556.00Current price is: ₹556.00.
Commercial’s Practical Guide to GST Amnesty by V.S. Sudhir – 1st Edition 2025.
30 in stock
Commercial’s Practical Guide to GST Amnesty by V.S. Sudhir – 1st Edition 2025.
Commercial’s Practical Guide to GST Amnesty by V.S. Sudhir – 1st Edition 2025.
About the book
For a limited period, the GST Amnesty Scheme provides a waiver of interest and penalties for taxpayers on specific outstanding GST demands, helping to clear backlogs and promote compliance. A scheme announced in Budget 2024 offers relief for non-fraudulent cases from the initial years of GST and is currently active.
Who is eligible for the amnesty scheme?
The current GST Amnesty Scheme (under Section 128A) covers specific cases and time periods, mainly for non-fraudulent tax demands.
- Eligible cases: Tax demands arising from notices or orders under Section 73 (non-fraudulent) for the financial years 2017–18, 2018–19, and 2019–20.
- Special provisions: The scheme also includes cases where a Section 74 (fraud) notice was later reclassified and assessed under Section 73 by an appellate authority or court.
- Excluded cases:
- Matters involving fraud, willful misstatement, or suppression of facts.
- Cases related to erroneous refunds.
- Any GST appeals or writ petitions that have not been withdrawn.
Conditions to avail the benefits
To qualify for the amnesty scheme, a taxpayer must take the following steps:
- Payment of tax: Pay the full amount of the outstanding tax demand, as specified in the notice or order, by the designated deadline.
- Withdraw appeals: Formally withdraw any pending appeals or writ petitions related to the tax demand before applying for the waiver.
Application process
Follow these steps to apply for the waiver through the GST portal:
- Log in: Go to the official GST portal and navigate to “Services” > “User Services” > “My Applications”.
- Select application type: From the “Application type” dropdown, choose “Apply for Waiver Scheme under Section 128A” and click “New Application”.
- Choose the correct form:
- Form SPL-01: For cases where a notice or statement was issued, but no final order has been passed.
- Form SPL-02: For cases where a demand order has been issued, including those pending at the appellate level.
- Fill out the application:
- Enter the details of the demand order or notice.
- Provide details of the tax payment made, such as the DRC-03 acknowledgment reference number.
- Confirm the withdrawal of any pending appeals, if applicable.
- Upload documents: Attach all required supporting documents, including proof of tax payment and appeal withdrawal. Up to five files, each with a size limit of 5 MB, can be uploaded.
- File the application: After saving and previewing the form, submit it using either a Digital Signature Certificate (DSC) or an Electronic Verification Code (EVC).
- Generate ARN: An Application Reference Number (ARN) will be generated upon successful submission.
Key deadlines for the current scheme
For taxpayers with eligible demands for FY 2017–18, 2018–19, and 2019–20, these are the critical dates:
- March 31, 2025: The last date to pay the full tax amount.
- June 30, 2025: The deadline to file the waiver application (Form SPL-01 or SPL-02).
Post-filing process and potential outcomes
After a taxpayer files an amnesty application, the GST officer will verify the details, which can lead to one of the following outcomes:
- Approval: If the application is verified and found to be in order, the officer will issue Form GST SPL-04 to close the proceedings, formally waiving the interest and penalties.
- Show cause notice: If discrepancies are found, the officer will issue a Show Cause Notice (Form GST SPL-03). The taxpayer has one month to respond using Form GST SPL-04.
- Rejection: The application may be rejected (Form GST SPL-05) if the officer finds issues, such as incomplete payment, late filing, or an invalid declaration. The taxpayer has the option to appeal against the rejection.
Details :-
- Publisher : Commercial Law Publishers (India) Pvt. Ltd.
- Author : Sudhir V.S. & Lakshman Kumar Kadali
- Edition : 1st Edition 2025
- ISBN-13 : 9789356039445
- ISBN-10 : 9789356039445
- Language : English
- Binding : Paperback
| Publisher | Commercial Law Publishers (India) Pvt. Ltd. |
|---|---|
| Language | English |
| Author | V.S. Sudhir |
Only logged in customers who have purchased this product may leave a review.
Related products
Commercial’s Understanding of Provisions of Deemed Income by Ram Dutt Sharma
Master the complex legal fictions that turn undisclosed financial transactions into massive tax liabilities. Commercial's Understanding of Provisions of Deemed Income (1st Edition, 2026) is a highly focused reference manual authored by former Income Tax Officer Ram Dutt Sharma.
-
✔ The Finance Act 2026 Updates: Fully aligned with the Income Tax Act 2025, detailing the latest statutory treatments of income deemed to accrue or arise in India.
-
✔ Unexplained Wealth: Deep, operational analysis of deemed income arising from unexplained cash, investments, expenditure, and assets (Sections 68, 69, 69A-D).
-
✔ Insider Strategy: Written by a 35-year veteran of the Income Tax Department, providing unparalleled clarity for defending against scrutiny assessments and reassessments.
Foreign Trade Policy & Handbook of Procedures 2023 | S.C. Jain
Navigate India’s complex foreign trade regime with the updated 2nd Edition (2025) of Foreign Trade Policy and Handbook of Procedures 2023 (2 Volumes). Authored by indirect tax experts S.C. Jain, Shweta Jain, and Abhishek Jain, this comprehensive set is the ultimate reference for trade professionals.
-
✔ Complete Framework: Full text of FTP 2023, Handbook of Procedures, and the FTDR Act 1992.
-
✔ Practical Insights: Detailed coverage of incentives, exemptions (Advance Authorisation, EPCG), and export promotion schemes.
-
✔ Fully Updated: Includes the latest DGFT notifications, circulars, and allied laws impacting foreign trade (Customs, GST, FEMA).
Taxmann’s GST on Works Contract & Other Construction/EPC Contracts by Sudipta Bhattacharjee
Taxmann's GST on Works Contract & Other Construction/EPC Contracts by Sudipta Bhattacharjee, Rishabh Prasad, Abhishek Garg - 12th Edition 2026. First, this Taxmann publication provides the exact text on engineering agreements. Specifically, the authors detail the strict rules for infrastructure taxation. Furthermore, this twelfth edition covers all fundamental 2026 legal updates perfectly.
Bharat’s Company law Ready Reckoner (2 Vols) by Dr. D.K. Jain
Bharat's Company law Ready Reckoner (2 Volumes) by Dr. D.K. Jain - 28th Edition 2026. First, this Bharat publication provides a complete guide to company law. Specifically, it details the exact rules for corporate compliance perfectly. Furthermore, this 28th Edition 2026 covers all statutory amendments across two massive volumes.
Taxmann’s Income Tax Act – As Amended by Finance Act 2025
Taxmann's Income Tax Act - As Amended by Finance Act 2025 - 70th Edition 2025. This book seamlessly integrates all amendments from the Finance Act 2025 into a single authoritative text. It offers extensive annotations, cross-references, and legislative history, catering to practitioners, academics, and libraries. Separate divisions also cover the Finance Act 2025, STT, CTT, and the now-ended Equalisation Levy, ensuring a holistic overview of direct tax laws. A user-friendly layout—with marginal notes, footnotes, and a comprehensive subject index—enables efficient navigation. Backed by meticulous editorial accuracy, this volume remains a definitive guide to direct tax legislation.

Reviews
There are no reviews yet.