
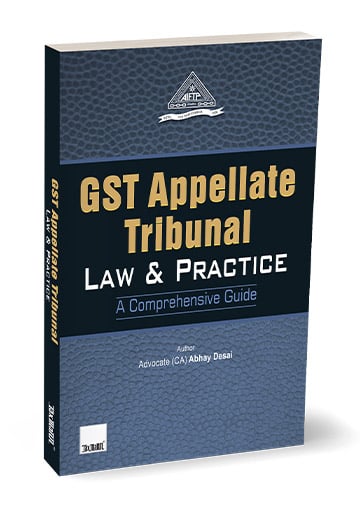
Taxmann’s GST Appellate Tribunal – Law & Practice | A Comprehensive Guide by AIFTP
₹985.00
Taxmann’s GST Appellate Tribunal – Law & Practice | A Comprehensive Guide by AIFTP – 1st Edition November 2025. GST Appellate Tribunal – Law & Practice | A Comprehensive Guide is a definitive, practitioner-oriented handbook on the GST Appellate Tribunal (GSTAT), blending doctrinal clarity with practical litigation strategy. It traces the full journey of GST appeals—from constitutional foundations and tribunal architecture to nuanced procedural requirements, jurisdictional principles, and representation techniques. Supported by insights from 200+ landmark judgments, the book bridges the gap between GST legislation and real-world appellate practice. Organised across four thematic parts with extensive appendices, the 2026 Edition authored by Advocate (CA.) Abhay Desai stands as the first comprehensive publication on GSTAT by AIFTP. It is an essential resource for tax professionals, industry practitioners, litigants, researchers, and government officials involved in GST disputes.
10 in stock
Taxmann’s GST Appellate Tribunal – Law & Practice | A Comprehensive Guide by AIFTP – 1st Edition November 2025.
Taxmann’s GST Appellate Tribunal – Law & Practice | A Comprehensive Guide by AIFTP – 1st Edition November 2025.
Incorporating:
GST Appellate Tribunal – Law & Practice | A Comprehensive Guide is an expansive and meticulously structured litigation manual on the Goods and Services Tax Appellate Tribunal (GSTAT). Serving both as a doctrinal reference and a practical handbook, the book traverses the complete spectrum of GST appellate jurisprudence—beginning with constitutional underpinnings and the theory of appellate remedies, progressing through the institutional architecture and functioning of GSTAT, and culminating in detailed procedural guidance, practice strategy, and the emerging role of AI in adjudication. Organised across four thematic parts supplemented by extensive appendices, this work stands as the first comprehensive publication on GSTAT released under the banner of the All India Federation of Tax Practitioners (AIFTP). It is purposefully designed to bridge the gap between statutory GST law and the operational realities of litigation before the Tribunal. The text incorporates over 200 judicial analyses, offering nuanced commentary on disputes, jurisdictional doctrines, appellate structure, procedural compliance, and best practices for effective representation.
This book is intended for the following audience:
- Tax Practitioners, Advocates & Chartered Accountants appearing before the GST Appellate Tribunal
- In-house Tax & Compliance Teams of trade and industry dealing with GST disputes
- Litigants, Consultants & GST Advisors involved in appellate or writ strategy
- Academicians, Researchers & Students studying GST adjudication and appellate remedies
- Government Officers & Tribunal Officials seeking clarity on GSTAT structure, procedures, and jurisdiction
The Present Publication is the 2026 Edition, authored by Advocate (CA.) Abhay Desai, commissioned by AIFTP and published by Taxmann. The noteworthy features of the book are as follows:
- [Complete Coverage of the GSTAT Ecosystem] The book explains the genesis of GST disputes, the evolution of tribunals in India, and the constitutional challenges surrounding the current structure of GSTAT. It clarifies the distinction between writ and appellate remedies and places the GST appellate system within its broader statutory framework
- [Deep Dive into Structure & Functioning of GSTAT] It provides clear explanations of:
- Principal Bench & State Benches
- Circuit Benches and territorial jurisdiction for each State
- Composition, appointment, qualifications, tenure, salaries, and service conditions of Members
- Procedural rules governing hearings, registries, e-filing, and virtual proceedings
- [Practitioner-oriented Procedural Guidance] The core of the book is a detailed, practical treatment of Tribunal procedures, including:
- Appealability of orders
- Identification of the ‘aggrieved person’
- Departmental appeals and review powers
- Filing requirements, digital forms, and documentary annexures
- Limitation, condonation, and judicial interpretation of ‘sufficient cause’
- Pre-deposit rules, deemed stay, and refund of deposits
- Additional grounds, additional evidence, and cross-objections
- Adjournments, ex parte orders, recall, review, and rectification
- Drafting of pleadings, affidavits, and written submissions
- [Case-law Driven Approach] Over 200 Supreme Court and High Court judgments are analysed to support the interpretation of appellate remedies, natural justice, jurisdiction, pre-deposit, limitation, ITC disputes, retrospective amendments, and tribunal functioning
- [Technology, E-Governance & AI] A full chapter examines how technology and artificial intelligence will influence legal research, drafting, evidence handling, and decision-making before GSTAT
The coverage of the book is as follows:
- Background & Foundations
- Why Disputes Arise Under GST – Constitutional conflicts, ambiguous drafting, frequent amendments, ITC mismatches, procedural lapses, retrospective changes, jurisdictional overlap, troublesome advance rulings, extended limitation, technical glitches on GSTN, reconciliation and transitional issues, and lack of accountability in administration
- Role & Nature of Tribunals – Historical evolution from early tax tribunals to CESTAT, ‘trappings of a court’, quasi-judicial powers, and the constitutional justification for tribunals in easing High Court arrears
- Constitutional Scheme & Challenges
- Articles 323A/323B and the power to create tribunals;
- Sampath Kumar, L. Chandra Kumar and the Madras Bar Association I–IV decisions on judicial review, separation of powers, independence of the judiciary, age/tenure issues, and selection/removal of members;
- How recent CGST amendments still fall short of Supreme Court directions (50-year age bar, 4-year tenure, panel of two names, removal procedures, absence of appointment timelines)
- Appellate V. Writ Remedies – Detailed comparison of statutory appeals under GST vs. writ petitions under Articles 226/227, including distilled principles on when High Courts can intervene despite alternate remedies
- GSTAT’s Structure, Composition & Jurisdiction
- Principal Bench at New Delhi; 31 State Benches with 16 circuit sittings; tabular State-wise mapping of bench locations and their circuit seats
- Qualifications, appointment process, Search-cum-Selection Committees, tenure, salaries, allowances, HRA caps, leave and travel entitlements, and post-tenure restrictions on practice or employment
- Subject-matter jurisdiction; appeals against orders of Appellate/Revisionary authorities, anti-profiteering matters, and exclusive jurisdiction of Principal Bench for place-of-supply and notified IGST/ISD/online gaming issues
- Territorial jurisdiction; district-wise allocation to each State Bench, ensuring clarity on where appeals must be filed
- Procedural & Substantive Practice before GSTAT
- Appealable Orders & Aggrieved Persons – Which orders can be appealed (including certain remand/enhancement orders and quasi-judicial communications), and who qualifies as a ‘person aggrieved’ (with case-laws)
- Departmental Appeals – Commissioner’s review powers, ‘legality or propriety’ test, and limits on expanding grounds beyond the review order
- Filing of Appeals
- Electronic filing through Forms GST APL-05/06/07
- Digital signature/e-verification
- Content requirements (statement of facts, grounds, annexures, issue-wise quantification, case history)
- Treatment of defects, translation of vernacular documents, and rules on authorisation and service
- Limitation & Condonation – Computation of three-month/six-month periods, extended timelines for old orders, President’s staggered-filing directions, exclusion of time when pursuing a wrong forum, and Supreme Court guidance on “sufficient cause” and public-interest delays.
- Pre-deposit & Deemed Stay
- Calculation of admitted vs disputed dues
- 10% pre-deposit (with cap) for tax/penalty orders
- Use of Electronic Credit Ledger and adjustment of investigation-stage payments
- Automatic stay of recovery once the statutory deposit is paid
- Refund of pre-deposit with interest upon success or remand
- Additional Grounds & Evidence – When new legal issues or documents can be raised/produced at the Tribunal stage, safeguards for the other side, and the Tribunal’s power to call for further evidence or witnesses
- Adjournments & Ex Parte Orders – Three-adjournment limit per party, but with a clear emphasis—based on Supreme Court precedent—that appeals must ultimately be decided on merits, not dismissed purely for non-appearance
- Cross Appeals & Cross Objections – Distinction between independent cross-appeals and cross-objections; rights of respondents to support favourable orders without necessarily filing cross-objections
- Doctrine of Precedents & Larger Bench – Binding nature of Supreme Court and High Court law, co-ordinate bench discipline, when to refer to a Larger Bench, and how ratio decidendi is to be extracted from judgments
- Summons, Cross-examination & Evidence – GSTAT’s civil-court-like powers to summon witnesses, issue commissions, record depositions, administer oaths, and order cross-examination—plus rules on witness allowances and interpreter fees
- Orders & Pronouncements – Writing, signing, and pronouncing orders; 30-day outer limit from final hearing for pronouncement; communication of certified copies; and record management
- Approach of Professionals & Role of AI
- Practical Tips for Preparing GSTAT Matters – File strategy, brief writing, compilation of case-law, oral submissions, and coordination between statutory appeals and writ petitions.
- Discussion on how AI tools may reshape legal research, drafting, prediction of outcomes, and document organisation, and the ethical and institutional questions this raises for courts and tribunals
The structure of the book is as follows:
- Part I – Background & Foundations
- Causes of disputes
- Role and history of tribunals
- Constitutional challenges (Articles 323A/323B, MBA cases)
- Nature of appellate remedies and writ jurisdiction
- Statutory framework of GST appeals
- Part II – Structure, Composition & Functioning of GSTAT
- Bench structure, Principal/State/Circuit Benches
- Appointment, qualifications, tenure, emoluments, removal
- GSTAT (Procedure) Rules and financial/administrative powers of the President
- Subject-matter and territorial jurisdiction
- Part III – Procedural & Substantive Practice
- Appealability, aggrieved persons, departmental appeals
- Filing, limitation, condonation, pre-deposit, and return of deposits
- Additional grounds/evidence, adjournments, cross-appeals/objections
- Doctrine of precedents, Larger Bench, third-member references
- Summons, cross-examination, interim applications, ex parte orders
- National Litigation Policy, statutory fees, and other procedural issues
- Part IV – Approach of Professionals and Role of AI
- Practical litigation techniques before GSTAT
- Future of appellate practice in a technology-driven environment
- Appendices & Back-matter
- Extracts of the CGST Act/Rules relevant to appeals and GSTAT
- GSTAT (Procedure) Rules 2025 & Forms
- E-filing Manual
- List of Cases and a comprehensive Subject Index.
Details
- Binding : Softcover
- Publisher : Taxmann
- Author : All India Federation of Tax Practitioners, Abhay Desai
- Edition : 1st Edition 2026
- Language : English
- ISBN-10 : 9789371268066
- ISBN-13 : 9789371268066
| Publisher | Taxmann |
|---|---|
| Language | English |
| Author | All India Federation of Tax Practitioners |
Only logged in customers who have purchased this product may leave a review.
Related products
Commercial’s Understanding of Provisions of Deemed Income by Ram Dutt Sharma
Master the complex legal fictions that turn undisclosed financial transactions into massive tax liabilities. Commercial's Understanding of Provisions of Deemed Income (1st Edition, 2026) is a highly focused reference manual authored by former Income Tax Officer Ram Dutt Sharma.
-
✔ The Finance Act 2026 Updates: Fully aligned with the Income Tax Act 2025, detailing the latest statutory treatments of income deemed to accrue or arise in India.
-
✔ Unexplained Wealth: Deep, operational analysis of deemed income arising from unexplained cash, investments, expenditure, and assets (Sections 68, 69, 69A-D).
-
✔ Insider Strategy: Written by a 35-year veteran of the Income Tax Department, providing unparalleled clarity for defending against scrutiny assessments and reassessments.
Commentary on Income Tax (Set of 2 Vols) | Ashok Saraf 2026
Navigate the sweeping changes of India's new direct tax regime with Bharat's Commentary on Income Tax (Set of 2 Volumes). Authored by Senior Advocate Dr. Ashok Saraf and CA Dr. Ayush Saraf, this 1st Edition (2026) provides an authoritative, section-by-section analysis of the newly enacted Income-tax Act 2025.
-
✔ Complete Statutory Transition: Exhaustive commentary on the new Income-tax Act 2025, amended by the Finance Act 2026.
-
✔ Corporate & Business Focus: Deep-dive analysis into the computation of business profits, depreciation, and capital gains.
-
✔ Expert Authorship: Blends decades of constitutional litigation experience with modern corporate accounting (Ind AS) expertise.
Taxmann’s GST on Works Contract & Other Construction/EPC Contracts by Sudipta Bhattacharjee
Taxmann's GST on Works Contract & Other Construction/EPC Contracts by Sudipta Bhattacharjee, Rishabh Prasad, Abhishek Garg - 12th Edition 2026. First, this Taxmann publication provides the exact text on engineering agreements. Specifically, the authors detail the strict rules for infrastructure taxation. Furthermore, this twelfth edition covers all fundamental 2026 legal updates perfectly.
Taxmann’s Guide to Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT) – 2nd Edition 2022
Taxmann's Guide to Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT) - 2nd Edition 2022. This book provides a comprehensive analysis of Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT). The analysis is done in light of the Income-tax Act 1961, Income-tax Rules 1962, and Relevant Case Laws. This book is amended by the Finance Act 2022.

Reviews
There are no reviews yet.