

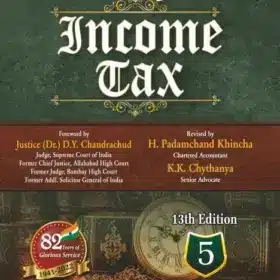
Bharat’s Law of Income Tax (Volume 4) By Sampath Iyengar – 13th Edition 2024
Original price was: ₹2,995.00.₹2,546.00Current price is: ₹2,546.00.
Bharat’s Law of Income Tax (Volume 4) By Sampath Iyengar – 13th Edition 2024.
10 in stock
Bharat’s Law of Income Tax (Volume 4) By Sampath Iyengar – 13th Edition 2024.
Bharat’s Law of Income Tax (Volume 4) By Sampath Iyengar – 13th Edition 2024.
About Law of Income Tax (Volume 4) By Sampath Iyengar
Sampath Iyengar’s Law of Income Tax has maintained its reputation as a commentary, exhaustive and encyclopedic in its sweep, and as a veritable warehouse of all the available information on the subject, besides carrying critical and in-depth comments. It is the most authentic referencer, which has stood the test of time during the last eight decades and has retained its pristine glory. This set provides not only the necessary access to all the relevant information, but also the expertise and the experience of the authors, present and past. Conflicting views are highlighted. Precedents are not merely listed, but their rationale analysed. This book has always been different in not being content with mere listing of cases, but by providing enough material to tackle any problem that may arise. No wonder it is being referred and cited as an authority at all levels of judicial interpretation – Income-tax Department, ITAT, High Courts, Supreme Court and even Authority for Advance Rulings.
While India celebrates its 75 years of Independence, Sampath Iyengar has helped the professionals, tax administrators and the judiciary for the last over 80 years in finding solutions to their tax issues. No effort is spared in the present edition to maintain the reputation, which this book has gained in the field of income-tax law for the past eight decades and more.
This locus classics has enjoyed the privilege of patronage from the profession of chartered accountants, tax practitioners, consultants, advisors, advocates, corporate executives, tax administrators and the judiciary.
Volume 4
D.—Profits & gains of business or profession
33. Development rebate
33A. Development allowance
33AB. Tea Development Account, Coffee Development Account and Rubber Development Account
33ABA. Site Restoration Fund
33AC. Reserves for shipping business
33B. Rehabilitation allowance
34. Conditions for depreciation allowance and development rebate
34A. Restriction on unabsorbed depreciation and unabsorbed investment allowance for limited period in case of certain domestic companies
35. Expenditure on scientific research
35A. Expenditure on acquisition of patent rights or copyrights
35AB. Expenditure on know-how
35ABA. Expenditure for obtaining right to use spectrum for telecommunication services
35ABB. Expenditure for obtaining licence to operate telecommunication services
35AC. Expenditure on eligible projects or schemes
35AD. Deduction in respect of expenditure on specified business
[35B. Omitted by the Direct Tax Laws (Amendment) Act, 1987, w.e.f. 1-4-1989]
[35C. Omitted by the Direct Tax Laws (Amendment) Act, 1987, w.e.f. 1-4-1989]
[35CC. Omitted by the Direct Tax Laws (Amendment) Act, 1987, w.e.f. 1-4-1989]
35CCA. Expenditure by way of payment to associations and institutions for carrying out rural development programmes
35CCB. Expenditure by way of payment to associations and institutions for carrying out programmes of conservation of natural resources
35CCC. Expenditure on agricultural extension project
35CCD. Expenditure on skill development project
35D. Amortisation of certain preliminary expenses
35DD. Amortisation of expenditure in case of amalgamation or demerger
35DDA. Amortisation of expenditure incurred under voluntary retirement scheme
35E. Deduction for expenditure on prospecting, etc., for certain minerals
36. Other deductions
37. General
38. Building, etc., partly used for business, etc., or not exclusively so used
[39. Omitted by the Direct Tax Laws (Amendment) Act, 1987, w.e.f. 1-4-1989]
40. Amounts not deductible
40A. Expenses or payments not deductible in certain circumstances
SUBJECT INDEX
Details :
- Publisher : Bharat Law House Pvt. Ltd.
- Author : Sampath Iyengar Revised by H. Padamchand Khincha and Chythanya K.K
- Edition : 13th Edition 2024
- ISBN-13 :
- ISBN-10 :
- Language : English
- Binding : Hardcover
| Author | Sampath Iyengar |
|---|---|
| Publisher | Bharat Law House Pvt. Ltd. |
| Language | English |
Only logged in customers who have purchased this product may leave a review.
Related products
Foreign Trade Policy & Handbook of Procedures 2023 | S.C. Jain
Navigate India’s complex foreign trade regime with the updated 2nd Edition (2025) of Foreign Trade Policy and Handbook of Procedures 2023 (2 Volumes). Authored by indirect tax experts S.C. Jain, Shweta Jain, and Abhishek Jain, this comprehensive set is the ultimate reference for trade professionals.
-
✔ Complete Framework: Full text of FTP 2023, Handbook of Procedures, and the FTDR Act 1992.
-
✔ Practical Insights: Detailed coverage of incentives, exemptions (Advance Authorisation, EPCG), and export promotion schemes.
-
✔ Fully Updated: Includes the latest DGFT notifications, circulars, and allied laws impacting foreign trade (Customs, GST, FEMA).
Taxmann’s Direct Taxes Ready Reckoner by Vinod K Singhania
Taxmann's Direct Taxes Ready Reckoner by Vinod K Singhania - 50th Edition March 2026 (A.Y. 2026-27) & (Tax Year 2026-27). First, this Taxmann publication provides the exact tax rates. Specifically, author Vinod K Singhania details strict tax planning. Furthermore, this 50th Edition covers all fundamental assessment year updates perfectly.
Taxmann’s MSME Digest By Mukesh Mohan Gupta
Taxmann's MSME Digest By Mukesh Mohan Gupta - 1st Edition 2026. First, the MSME Digest serves as a comprehensive legal guide. Specifically, it consolidates the evolving laws governing India's Micro, Small, and Medium Enterprises (MSME) sector. Furthermore, this practice-ready reference brings together landmark decisions from the Supreme Court and various High Courts.

Taxmann’s Guide to Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT) – 2nd Edition 2022
Taxmann's Guide to Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT) - 2nd Edition 2022. This book provides a comprehensive analysis of Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT). The analysis is done in light of the Income-tax Act 1961, Income-tax Rules 1962, and Relevant Case Laws. This book is amended by the Finance Act 2022.
Reviews
There are no reviews yet.