
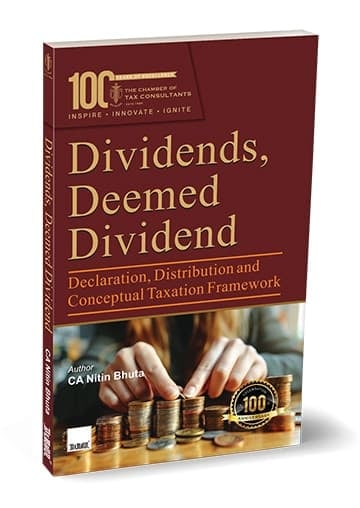
Taxmann’s Dividends & Deemed Dividend Taxation Framework by Nitin Bhuta
₹485.00
A dividend looks like the simplest transaction in corporate finance—until it hits the tax code. Dividends, Deemed Dividend—Declaration, Distribution and Conceptual Taxation Framework by CA. Nitin Bhuta compresses a subject that ordinarily sprawls across four volumes into a single, masterful, 142-page guide.
-
✔ The ITA 2025 Transition: Maps the newly enacted Income-tax Act 2025 against the 1961 Act, analyzing whether 70 years of judicial precedent still hold weight.
-
✔ Multi-disciplinary Approach: Reads Company Law (Sec 123), Tax Law (Sec 2(40)), FEMA, and Audit (Rule 11(f)) as one interconnected system.
-
✔ Positions, Not Hedges: Tackles highly contested controversies (e.g., deemed dividends on capital reduction, buy-backs, and intra-group loans) with candid risk ratings and reasoned views.
100 in stock
Taxmann’s Dividends, Deemed Dividend—Declaration, Distribution and Conceptual Taxation Framework by Nitin Bhuta (The Chamber of Tax Consultants) – Edition July 2026.
By the time a single rupee reaches a shareholder, it has had to survive Section 123 of the Companies Act 2013, the famously elastic definition of deemed dividend under the Income-tax Act, strict FEMA rules, and applicable DTAAs. Dividends, Deemed Dividend, published exclusively by Taxmann and commissioned by The Chamber of Tax Consultants, holds all of this in a single hand. Drawing on 33 years of practice, CA. Nitin Bhuta delivers a multi-disciplinary text that refuses to read tax law in a vacuum—proving that a defective declaration under company law is the seed of a tax dispute.
Navigating the Transition: ITA 1961 to ITA 2025
This is, unusually, a book written from inside a statutory transition. It does not merely note that the Income-tax Act 2025 exists; it maps it rule-by-rule against the 1961 Act.
-
Comparative Tables: Features two full mapping tables (e.g., Sec 2(22) → 2(40), Sec 14A → 14), worth the price of admission for anyone advising across the changeover.
-
The Buy-Back Cliff: Dissects the omission of sub-clause (f) from Section 2(40), explaining the critical cutoff: paid on or before 31-3-2026, it is a deemed dividend; paid on or after 1-4-2026, it is capital gains under Section 69.
-
Precedent Testing: Asks the question practitioners actually need answered: do the old judgments still work? Readers are expressly advised on how to test each historical pronouncement against the revised 2025 framework.
Deemed Dividend Controversies (The Litigation Engine)
The book features a 30+ page forensic treatment of Section 2(22)/Section 2(40). Every sub-clause is analyzed for its cumulative conditions and stress-tested scenario by scenario.
-
Scenario Tables: Over twenty transaction types—including overdrafts, corporate guarantees, trade advances, and call money—are sorted in a two-column grid. You don’t read the chapter; you find your row and the governing precedent.
-
Positions, Not Hedges: Contested questions are framed as “Posers” and answered with the author’s reasoned view (e.g., whether Section 56(2)(x) is triggered on capital reduction), complete with candid risk ratings.
-
The Audit Interface: Provides direct guidance on Clause 36A of Form 3CD (Clause 48 of Form 26 under ITR 2026), detailing exactly what must be reported and what the auditor is not required to opine on. Includes a ready-to-use, 44-point Corporate Dividend Audit Checklist for Rule 11(f) compliance.
Who Should Buy This Book?
-
Chartered Accountants & Tax Consultants: For quantifying deemed dividend exposure, determining withholding, and defending positions in assessments.
-
Statutory & Tax Auditors: Essential for discharging the specific reporting duties required under Rule 11(f) and Form 3CD.
-
CFOs & Corporate Boards: Crucial for closely held groups where intra-group loans routinely mutate into deemed dividends, carrying personal exposure for directors.
-
Advocates & Litigators: The four-way index (Judicial Citations, Alphabetical, Subject-wise, Section-wise) ensures immediate retrieval of case law during appellate proceedings.
About the Author
CA. Nitin Bhuta
CA. Nitin Bhuta is the proprietor of Nitin Bhuta & Co., Chartered Accountants, Mumbai, a practice celebrating its 33rd year in 2026. A 13th All-India Rank Holder in the ICAI Intermediate Examination, his professional engagement with the ICAI is extensive, including appointments to the Direct Tax Committee and representation on the New Income Tax Website.
A founder member of the Confederation of GST Professionals and Industries (CGPI), he writes a monthly column for the Malad Chamber of Tax Consultants and regularly contributes to ICAI publications, including Guidance Notes on Tax Audit. He is a sought-after speaker at WIRC, NACIN, and study circles across the country.
Details
- Binding : Paperback
- Publisher : Taxmann
- Author : The Chamber of Tax Consultants
- Edition : July 2026
- Language : English
- ISBN-10 : 9789375619956
- ISBN-13 : 9789375619956
| Publisher | Taxmann |
|---|---|
| Author | The Chamber of Tax Consultants |
| Language | English |
Only logged in customers who have purchased this product may leave a review.
Related products
Commentary on Income Tax (Set of 2 Vols) | Ashok Saraf 2026
Navigate the sweeping changes of India's new direct tax regime with Bharat's Commentary on Income Tax (Set of 2 Volumes). Authored by Senior Advocate Dr. Ashok Saraf and CA Dr. Ayush Saraf, this 1st Edition (2026) provides an authoritative, section-by-section analysis of the newly enacted Income-tax Act 2025.
-
✔ Complete Statutory Transition: Exhaustive commentary on the new Income-tax Act 2025, amended by the Finance Act 2026.
-
✔ Corporate & Business Focus: Deep-dive analysis into the computation of business profits, depreciation, and capital gains.
-
✔ Expert Authorship: Blends decades of constitutional litigation experience with modern corporate accounting (Ind AS) expertise.
Bharat’s Financial Statements of Non-Corporate Entities by CA. Kamal Garg
Bharat's Financial Statements of Non-Corporate Entities by CA. Kamal Garg - 2nd Edition 2026. First, this Bharat publication provides the exact, practice-ready text on reporting guidelines, ledger disclosures, and accounting formats for un-incorporated setups in India. Specifically, written by CA. Kamal Garg, this manual outlines the strict rules of preparing books for non-corporate setups. Furthermore, this 2nd edition incorporates all active disclosure parameters and structural compliance revisions running flawlessly through 2026.
Taxmann’s Tax Prosecution under Income-tax/GST & Black Money Laws by Gagan Kumar
Taxmann's Tax Prosecution under Income-tax/GST & Black Money Laws by Gagan Kumar - 5th Edition 2026. First, this Taxmann publication provides the exact text on criminal tax liabilities. Specifically, author Gagan Kumar details the strict rules for tax prosecution. Furthermore, this fifth edition covers all fundamental 2026 statutory frameworks perfectly.
Bharat’s Company law Ready Reckoner (2 Vols) by Dr. D.K. Jain
Bharat's Company law Ready Reckoner (2 Volumes) by Dr. D.K. Jain - 28th Edition 2026. First, this Bharat publication provides a complete guide to company law. Specifically, it details the exact rules for corporate compliance perfectly. Furthermore, this 28th Edition 2026 covers all statutory amendments across two massive volumes.
Taxmann’s Income Tax Act – As Amended by Finance Act 2025
Taxmann's Income Tax Act - As Amended by Finance Act 2025 - 70th Edition 2025. This book seamlessly integrates all amendments from the Finance Act 2025 into a single authoritative text. It offers extensive annotations, cross-references, and legislative history, catering to practitioners, academics, and libraries. Separate divisions also cover the Finance Act 2025, STT, CTT, and the now-ended Equalisation Levy, ensuring a holistic overview of direct tax laws. A user-friendly layout—with marginal notes, footnotes, and a comprehensive subject index—enables efficient navigation. Backed by meticulous editorial accuracy, this volume remains a definitive guide to direct tax legislation.
Reviews
There are no reviews yet.