
Capital Gains (Law, Practice & Litigation) | CA Akash Garg 2026
Original price was: ₹2,495.00.₹1,871.00Current price is: ₹1,871.00.
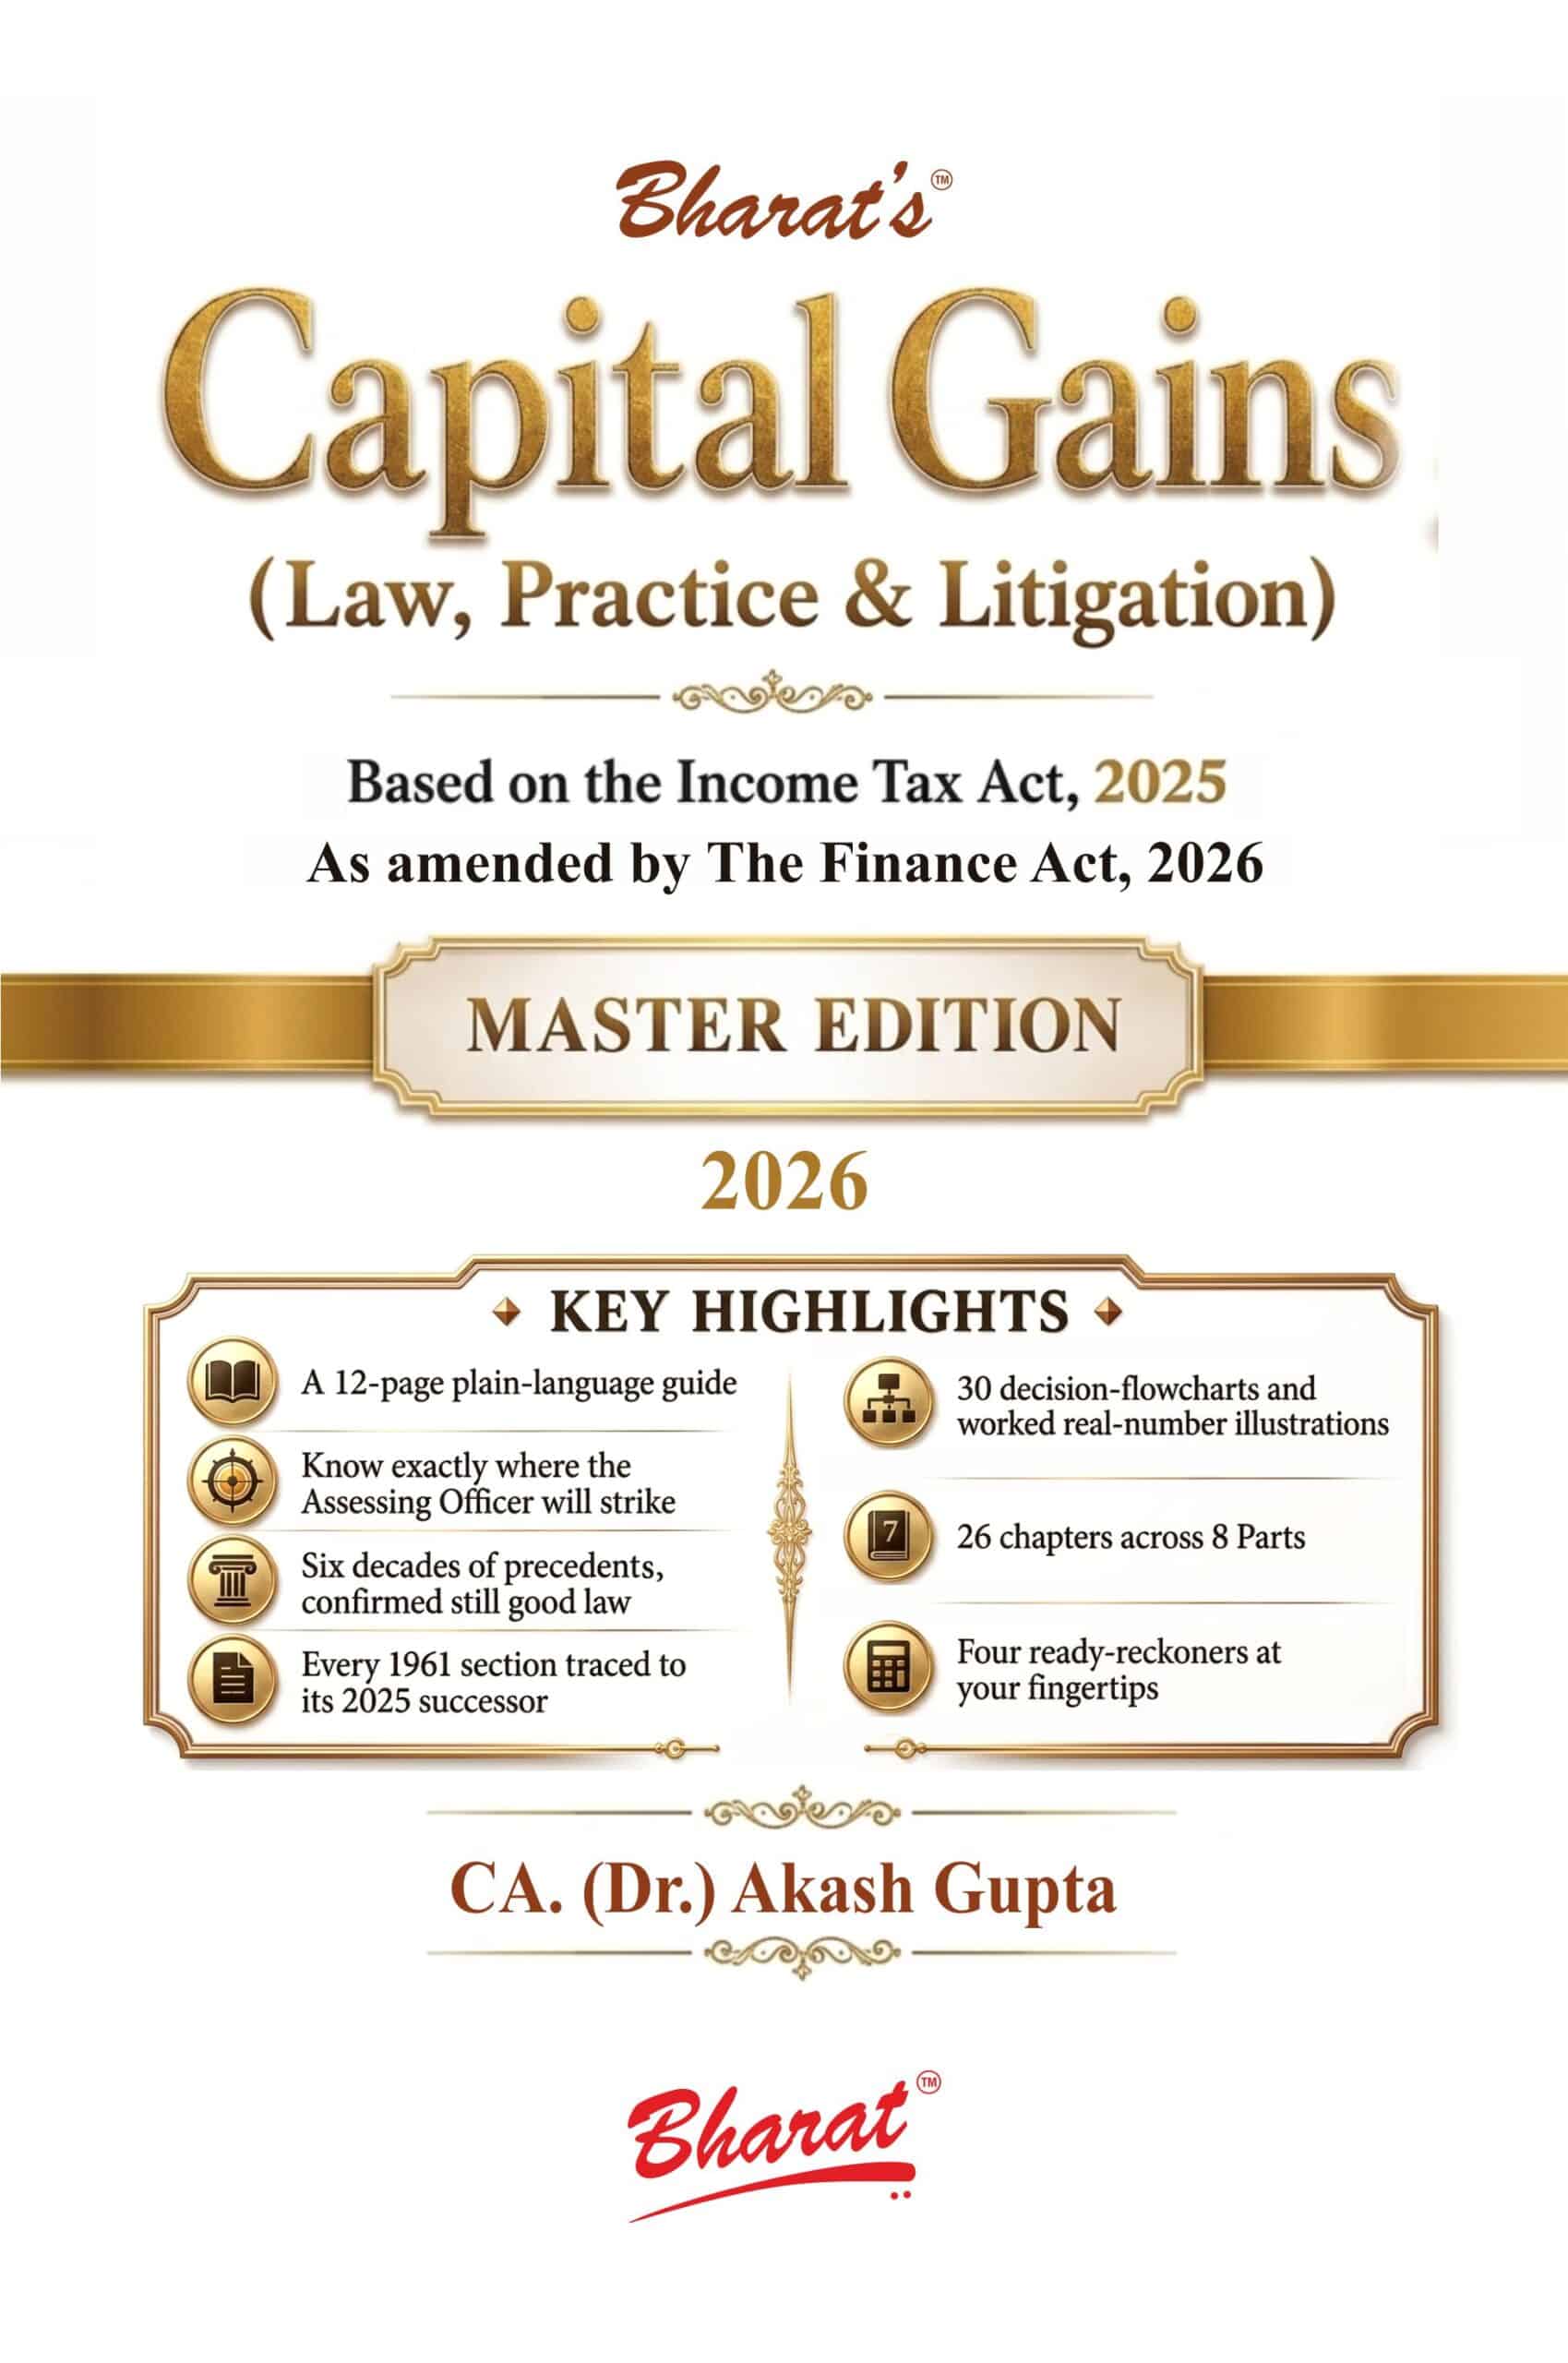
Navigate the most scrutinized area of Indian direct tax with Bharat’s Capital Gains (Law, Practice & Litigation). Authored by taxation scholar and corporate adviser CA. (Dr.) Akash Garg, this 1st Edition (2026) provides an exhaustive, boardroom-level analysis of capital gains under the newly enacted Income-tax Act 2025.
-
✔ The 2025 Regime: Deep-dive into the new computational engine, including the exact treatment of full value of consideration, cost of acquisition, and improvement.
-
✔ Reinvestment Exemptions: Master the nuances of residential house exemptions, the ₹10 Crore cap, and the Section 86 trap.
-
✔ Corporate Transactions: Dedicated chapters on complex corporate events—slump sales, liquidation, buybacks, and indirect transfers.
100 in stock
Bharat’s Capital Gains (Law, Practice & Litigation) by CA. (Dr.) Akash Garg – 1st Edition 2026.
Capital Gains taxation is undergoing a massive structural shift under the Income-tax Act 2025. Bharat’s Capital Gains (Law, Practice & Litigation) is an authoritative, purpose-built desk reference that bridges statutory academic analysis with practical, boardroom-level direct tax advisory. Authored by CA. (Dr.) Akash Garg, this 2026 edition systematically dismantles the complexities of the new charging architecture, the computation engine, and the critical reinvestment exemptions that drive modern tax planning.
Structural Breakdown: The 2025 Legal Framework
The book is organized into eight distinct parts, moving logically from the foundational charging architecture through to high-stakes corporate litigation strategies:
-
Part I & II: Architecture & Computation: Understand exactly what constitutes a “transfer” and master the mechanics of computation under the 2025 Act. Includes granular analysis of the Cost of Acquisition, Cost of Improvement, and Expenditure on Transfer.
-
Part III: Special Computation Regimes: Essential reading for active investors and corporate advisors. Covers the specific capital gains treatment of Market Linked Debentures, Specified Mutual Funds, Unlisted Bonds, and Business Trusts. Furthermore, it dissects complex corporate transactions including Liquidation, Buybacks, Conversion, and Slump Sales.
-
Part IV: Reinvestment Exemptions (Crucial for Real Estate): An exhaustive look at wealth preservation. Covers exemptions on Residential Houses (navigating the ₹10 Crore Cap and the Section 86 trap), Agricultural Land (the three-layer framework and RFCTLARR carve-out), and Specified Bonds (the ₹50 Lakh route).
Litigation Strategy & Practitioner Tools
Unlike pure academic texts, this book is built for practice.
-
Litigation & Case Studies (Part VII): Details effective litigation strategies and judicial principles, supported by real-life case studies and scenarios.
-
Procedural Infrastructure (Part VI): Clarifies documentation, reporting requirements, and the specific procedures for Reference to a Valuation Officer under Section 91.
-
Practitioner Reference (Part VIII): Features highly actionable tools including FAQs for professionals, procedural checklists, complete section mapping, and the latest Tax Rate Charts for Capital Gains.
Who Should Buy This Book?
-
Chartered Accountants & Tax Consultants: The ultimate desk reference for structuring client portfolios, managing real estate transactions, and advising on corporate restructuring under the 2025 Act.
-
Corporate Legal Counsel & CFOs: Essential for navigating the tax implications of slump sales, buybacks, and indirect transfers.
-
High-Net-Worth Individuals & Real Estate Investors: Provides the exact legal frameworks required to optimize reinvestment exemptions (Section 54 series) and preserve long-term wealth.
About the Author
CA. (Dr.) Akash Garg CA. (Dr.) Akash Garg is a prominent Indian Chartered Accountant, taxation scholar, and corporate adviser specializing in direct tax litigation and financial reporting. Holding a Ph.D. in Taxation from Lucknow University, his professional expertise is unique in that it successfully bridges rigorous, statutory academic analysis with highly practical, boardroom-level direct tax advisory.
Details :
- Publisher : Bharat Law House Pvt. Ltd.
- Author : CA. (Dr.) Akash Garg
- Edition : 1st Edition 2026
- ISBN-13 : 9788169449175
- ISBN-10 : 9788169449175
- Language : English
- Binding : Paperback
| Author | CA Akash Garg |
|---|---|
| Language | English |
| Publisher | Bharat Law House Pvt. Ltd. |
Only logged in customers who have purchased this product may leave a review.
Related products
Bharat’s Law, Practice & Procedure of GST Appeals by Dr. J.K. Mittal
Bharat's Law, Practice & Procedure of GST Appeals by Dr. J.K. Mittal - 1st Edition 2026. First, this Bharat publication provides the exact, practice-ready text on indirect tax litigation and dispute resolution in India. Specifically, written by Dr. J.K. Mittal, this definitive legal reference manual details the strict rules of managing appeal files. Furthermore, this 1st edition completely incorporates all recent operational guidelines and structural tribunal mandates running smoothly through 2026.
Taxmann’s GST on Works Contract & Other Construction/EPC Contracts by Sudipta Bhattacharjee
Taxmann's GST on Works Contract & Other Construction/EPC Contracts by Sudipta Bhattacharjee, Rishabh Prasad, Abhishek Garg - 12th Edition 2026. First, this Taxmann publication provides the exact text on engineering agreements. Specifically, the authors detail the strict rules for infrastructure taxation. Furthermore, this twelfth edition covers all fundamental 2026 legal updates perfectly.
Taxmann’s Direct Taxes Ready Reckoner by Vinod K Singhania
Taxmann's Direct Taxes Ready Reckoner by Vinod K Singhania - 50th Edition March 2026 (A.Y. 2026-27) & (Tax Year 2026-27). First, this Taxmann publication provides the exact tax rates. Specifically, author Vinod K Singhania details strict tax planning. Furthermore, this 50th Edition covers all fundamental assessment year updates perfectly.


Reviews
There are no reviews yet.