
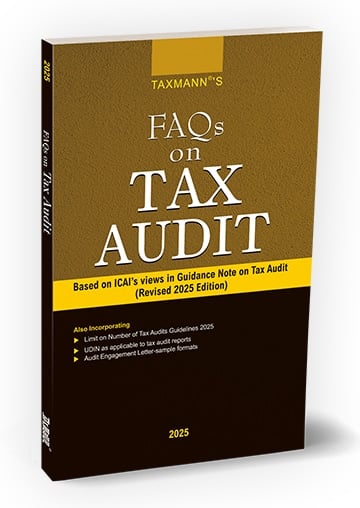
Taxmann’s FAQs on Tax Audit – Edition September 2025
Original price was: ₹1,395.00.₹1,116.00Current price is: ₹1,116.00.
Taxmann’s FAQs on Tax Audit – Based on ICAI’s Views in Guidance Note on Tax Audit [Revised 2025 Edition] – Edition September 2025. FAQs on Tax Audit is a practitioner-oriented handbook that converts ICAI’s Guidance Note on Tax Audit (Revised 2025) into precise, clause-wise FAQs on section 44AB, mapping every 3CA/3CB/3CD requirement to procedures, documentation, and e-filing. It provides comprehensive ‘how-to-fill’ guidance for all Form 3CD clauses (Chapters 17–63), including specimen language, checklists, and cross-references to the Standards on Auditing and the GN. The 2025 Edition, which is expressly ‘Based on ICAI’s views’—clarifies the audit-cap transition (2008 rules → 2025 Guidelines) and UDIN essentials, including the one-UDIN-per-assignment rule. Utility-level walkthroughs simplify the Clauses 11, 32(e), 34(a)/(b), 42, 43, and 44, and the book includes ready-to-use engagement letters for 3CA-3CD/3CB-3CD—ideal for practising CAs, audit teams, CFOs/finance leaders, compliance functions, and learners.
30 in stock
Taxmann’s FAQs on Tax Audit – Based on ICAI’s Views in Guidance Note on Tax Audit [Revised 2025 Edition] – Edition September 2025.
Taxmann’s FAQs on Tax Audit – Based on ICAI’s Views in Guidance Note on Tax Audit [Revised 2025 Edition] – Edition September 2025.
Description
FAQs on Tax Audit is a practitioner‑oriented, clause‑wise handbook on tax audit under section 44AB. It distils the ICAI’s Guidance Note (GN) on Tax Audit (Revised 2025) into focused questions and answers, mapping every reporting requirement in Forms 3CA/3CB/3CD to practical procedures, documentation, and e‑filing steps. The Edition is specifically ‘Based on ICAI’s views in Guidance Note on Tax Audit’, ensuring alignment with the latest forms, utilities, and professional pronouncements. The book covers all Form 3CD clauses (Chapters 17–63) with ‘how‑to‑fill’ guidance, supported by specimen language, checklists, and cross‑references to Standards on Auditing and the Guidance Note.
This book is intended for the following audience:
- Chartered Accountants in practice handling tax audits of corporate and non‑corporate assessees
- Audit Partners, Managers & Articled Assistants who need clause‑wise, form‑linked answers
- CFOs/Finance Heads, Controllers & Tax Leads seeking to understand 44AB requirements, documentation and disclosures
- Internal Auditors & Compliance Teams aligning financial reporting with tax audit reporting
- Academics & Learners requiring an authoritative, FAQ‑based companion to the ICAI Guidance Note
The Present Publication is the 2025 Edition, updated till 30th August 2025. This book is edited by Taxmann’s Editorial Board, with the following noteworthy features:
- [Authoritative Alignment with ICAI 2025 Guidance Note] The coverage mirrors the structure and positions of the Revised 2025 Guidance Note on Tax Audit, including the requirement to incorporate SA‑700 style responsibility paragraphs within Form 3CA/3CB observations
- [Limit on Number of Tax Audits Guidelines] Clear answers on counting accepted assignments under the still‑operative 2008 rules through 31‑03‑2026, and what changes from 01‑04‑2026 under the 2025 Guidelines (e.g., revised TARs excluded from the cap, sharing of per‑partner limits disallowed)
- [UDIN—What to Generate & Where to Quote] Step‑by‑step on UDIN generation for tax audits, the four mandatory key fields for 44AB assignments, when separate UDINs are needed (e.g., Form 29B), and the ‘one UDIN per assignment’ rule for 3CA/3CB with 3CD
- [Clause‑wise, Utility‑first Guidance] E‑filing walkthroughs for tricky clauses—Clause 11 (books & documents), Clause 32(e) (speculation business), Clause 34(a)/(b) (TDS/TCS), Clause 42 (SFT Forms 61/61A/61B), Clause 44 (GST‑wise expenditure)—with exactly what to ‘Select/Add Details’ in the utility and what to keep in workpapers
- [Ready‑to‑use Engagement Letters] Sample audit engagement letters tailored for 3CA‑3CD (statutory audit already done) and 3CB‑3CD scenarios, including clauses on UDIN disclosures, digital‑signature safeguards, confidentiality, AML/anti‑corruption, end‑use, termination, and management representations
- [Case‑law & Guidance Note Based Positions] Integrated judicial references (e.g., treatment of reimbursements; classification nuances) and explicit GN‑2025 pointers throughout
The coverage of the book is as follows:
- Applicability & Thresholds (Section 44AB)
- Who must be audited; 10‑crore threshold where 95% receipts and payments are non‑cash; treatment of presumptive codes and the third proviso (further report by an accountant)
- Who Can/Can’t Audit
- Qualifications/disqualifications of the tax auditor; internal auditor/employee restrictions; appointment of CA firms; interaction with Section 288(2) ‘accountant’
- Cap on Audits—Old vs New Regime
- Counting under Council General Guidelines 2008 till 31‑03‑2026 (accepted assignments basis; multi‑year for same client counts separately; HO+branches = one assignment; joint audits count for each), and the 2025 Guidelines effective from 01‑04‑2026 (e.g., revised TARs excluded)
- Tax Audit Reports (3CA/3CB) & ‘Specified Date’
- Forms matrix; 30th September TAR filing cut‑off (for assessees subject to audit); pre‑issuance principles; signing practices; digital filing
- Standards on Auditing & Responsibility Paragraphs
- Where and how to embed SA‑700 style ‘assessee’s responsibility’ and ‘auditor’s/practitioner’s responsibility’ content inside Para 3 of Form 3CA/Para 5 of 3CB
- UDIN
- FAQs on who generates UDIN in firms, allocation among partners, no separate UDIN for 3CA/3CD (one assignment), and the mandatory fields for 44AB engagements; model AEL wording to disclose portal sharing
- Clause‑wise Drill‑downs (Form 3CD)
- Clause 11 (Books & Documents) – Inclusive definition of ‘document’ referencing Section 2(22AA) and how to fill the utility
- Clause 32(e) (Explanation to Section 73) – Identifying deemed speculation business and reporting approach
- Clause 33 (Chapter VI‑A/10A/10AA) – Section‑wise tabular reporting
- Clause 34(a)/(b) (TDS/TCS) – Verification steps, what to report, and the exact ‘Add Details’ fields
- Clause 42 (SFT—Forms 61/61A/61B) – Focusing on filing status and completeness of reporting, including where to list deficiencies if space is limited
- Clause 43 (CbCR u/s 286) – Filing status guidance (with no requirement to audit the CbCR contents—contrasted with Clause 42)
- Clause 44 (GST‑wise Expenditure) – What not to include (e.g., depreciation, bad debts), what must be reconciled, and how to treat Schedule‑III items like salaries
- Specimen Engagement Letters (Chapters 64–65)
- Complete AELs for 3CA‑3CD and 3CB‑3CD—with UDIN portal disclosure, digital‑signature controls, confidentiality, AML/anti‑corruption, governance communications, working papers, end‑use, and termination
- Appendix
- Relevant sections of the Income‑tax Act for quick reference
The structure of the book is as follows:
- 65 Chapters & Appendix – The text is sequenced to mirror a practitioner’s workflow: applicability → eligibility & limits → financial statements basis → standards & forms → UDIN/liabilities/revision → clause‑wise Form 3CD reporting → engagement letter templates
- FAQ Format – It enables quick look‑ups and precise answers aligned with ICAI’s positions
- Form‑linked Navigation – This ensures that preparers and reviewers can move seamlessly between statutory requirements and reporting clauses.
Details
Only logged in customers who have purchased this product may leave a review.
Related products
Foreign Trade Policy & Handbook of Procedures 2023 | S.C. Jain
Navigate India’s complex foreign trade regime with the updated 2nd Edition (2025) of Foreign Trade Policy and Handbook of Procedures 2023 (2 Volumes). Authored by indirect tax experts S.C. Jain, Shweta Jain, and Abhishek Jain, this comprehensive set is the ultimate reference for trade professionals.
-
✔ Complete Framework: Full text of FTP 2023, Handbook of Procedures, and the FTDR Act 1992.
-
✔ Practical Insights: Detailed coverage of incentives, exemptions (Advance Authorisation, EPCG), and export promotion schemes.
-
✔ Fully Updated: Includes the latest DGFT notifications, circulars, and allied laws impacting foreign trade (Customs, GST, FEMA).
Bharat’s Financial Statements of Non-Corporate Entities by CA. Kamal Garg
Bharat's Financial Statements of Non-Corporate Entities by CA. Kamal Garg - 2nd Edition 2026. First, this Bharat publication provides the exact, practice-ready text on reporting guidelines, ledger disclosures, and accounting formats for un-incorporated setups in India. Specifically, written by CA. Kamal Garg, this manual outlines the strict rules of preparing books for non-corporate setups. Furthermore, this 2nd edition incorporates all active disclosure parameters and structural compliance revisions running flawlessly through 2026.
Bharat’s Income Tax Act, 2025 (Pocket Edn.) – 39th Edition 2026
Bharat's Income Tax Act, 2025 (Pocket Edn.) - 39th Edition 2026. First, this Bharat publication provides the exact pocket-sized legal text on direct tax laws for professionals in India. Specifically, compiled by Bharat Law House, this compact reference book details the statutory rules of the newly active Income Tax Act, 2025. Furthermore, this 39th edition includes highly useful comments and cross-reference tables updated for easy use on the go.
Bharat’s Company law Ready Reckoner (2 Vols) by Dr. D.K. Jain
Bharat's Company law Ready Reckoner (2 Volumes) by Dr. D.K. Jain - 28th Edition 2026. First, this Bharat publication provides a complete guide to company law. Specifically, it details the exact rules for corporate compliance perfectly. Furthermore, this 28th Edition 2026 covers all statutory amendments across two massive volumes.
Taxmann’s Income Tax Act – As Amended by Finance Act 2025
Taxmann's Income Tax Act - As Amended by Finance Act 2025 - 70th Edition 2025. This book seamlessly integrates all amendments from the Finance Act 2025 into a single authoritative text. It offers extensive annotations, cross-references, and legislative history, catering to practitioners, academics, and libraries. Separate divisions also cover the Finance Act 2025, STT, CTT, and the now-ended Equalisation Levy, ensuring a holistic overview of direct tax laws. A user-friendly layout—with marginal notes, footnotes, and a comprehensive subject index—enables efficient navigation. Backed by meticulous editorial accuracy, this volume remains a definitive guide to direct tax legislation.

Reviews
There are no reviews yet.