
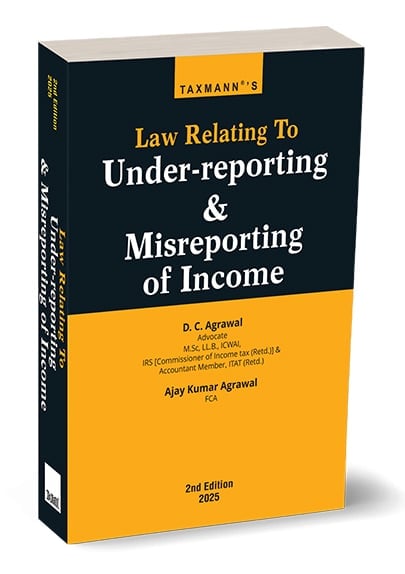
Taxmann’s Law Relating to Under-reporting & Misreporting of Income by D.C. Agrawal
Original price was: ₹1,395.00.₹1,116.00Current price is: ₹1,116.00.
Taxmann’s Law Relating to Under-reporting & Misreporting of Income- As Amended by Finance Act, 2025 by D.C. Agrawal – 2nd Edition 2025. This comprehensive book explores the legal framework of penalties for inaccurate income disclosures in Indian tax law, focusing on Section 270A (post-AY 2017–18) and covering both historical provisions (Section 271(1)(c)) and the latest amendments. It clarifies key concepts like under-reporting vs. misreporting, essential definitions, core legal principles, and over 30 model responses for practical penalty scenarios. Readers gain practical insights into the burden of proof, drafting defences, and how ‘mens rea’ applies to penalty proceedings. Authored by seasoned experts D.C. Agrawal and Ajay Kumar Agrawal, it is helpful for tax practitioners, legal professionals, finance experts, and academicians.
10 in stock
Taxmann’s Law Relating to Under-reporting & Misreporting of Income- As Amended by Finance Act, 2025 by D.C. Agrawal – 2nd Edition 2025.
Taxmann’s Law Relating to Under-reporting & Misreporting of Income- As Amended by Finance Act, 2025 by D.C. Agrawal – 2nd Edition 2025.
Description
This book comprehensively examines the legal framework for penalties on inaccurate income disclosures under the Indian Income Tax regime. It provides the readers with a thorough understanding of the historical and current provisions governing penalties, particularly focusing on Section 270A (covering assessment year 2017-18 onwards). It explains how under-reported and misreported income is dealt with, outlines important legal principles, clarifies essential definitions (such as ‘facts,’ ‘books of account,’ ‘evidence’), and provides sample replies to penalty notices.
This book is intended for the following audience:
- Tax Practitioners & Chartered Accountants – A resource for preparing effective submissions/defence in penalty proceedings
- Lawyers & Advocates – A reference for drafting arguments, understanding legislative intent, and citing relevant judgments on penalty matters
- Corporate Finance Professionals – Guidance on ensuring compliant reporting of income, minimising legal risks in corporate transactions, and preventing unwarranted penalties
- Students & Academicians – Helpful for the advanced study of taxation law, particularly penalty provisions, and for developing practical insights into assessment and appellate processes
The Present Publication is the 2nd Edition | 2025, updated till 30th March 2025. This book is authored by D.C. Agrawal and Ajay Kumar Agrawal, with the following noteworthy features:
- [Complete Coverage of Penalty Provisions]
- Detailed commentary on old penalty provisions under Section 271(1)(c) and their historical evolution
- Thorough analysis of the ‘under-reporting’ and ‘misreporting’ concepts introduced under Section 270A
- Discussion of related provisions such as Sections 270AA, 271AAC, 271AAB, 273B, and 274
- [Practical Draft Responses] Over 30 chapters are devoted to model submissions and responses to penalty notices. These help readers draft defences suited to their specific factual scenarios
- [Illustrative Case Studies & Examples] Landmark judicial rulings are distilled into easily understandable lessons, indicating how courts interpret under-reporting, misreporting, and the burden of proof
- [Guidance on Burden of Proof & Evidence] Comprehensive explanations of the burden of proof under penal provisions, along with a clear delineation of how the Indian Evidence Act principles apply in tax cases
- [Clarification on Mens Rea] Dedicated chapters dissect the concept of ‘mens rea’ (guilty mind) in the context of new penalty provisions and how it may or may not be relevant under Section 270A
- [Latest Amendments & Circulars] Incorporates relevant CBDT circulars/notifications that clarify or modify penalty procedures
- [Authored by Veteran Experts] Mr D.C. Agrawal (Advocate, former IRS officer, and retired ITAT Accountant Member) and Mr Ajay Kumar Agrawal (FCA, over thirty years in corporate consultancy and litigation) combine extensive domain knowledge and practical experience
The coverage of the book is as follows:
- Historical Perspective
- How penal provisions for concealment of income evolved from Section 271(1)(c) to the newly introduced Section 270A regime
- Principles of Penalty
- Examination of fundamental rules such as strict interpretation of penal statutes, the difference between civil and criminal liability, and how ‘penalty proceedings’ differ from ‘assessment proceedings’
- Under-reporting vs. Misreporting
- Clear demarcation between the two concepts, backed by definitions, examples, and judicial interpretation
- Draft Submissions
- More than thirty chapters are dedicated to likely scenarios—such as disallowances under Section 14A, additions on account of bogus purchases, transactions below stamp duty valuation, or not declaring interest on refunds—and how an assessee could respond to penalty notices
- Special Focus on Section 270AA
- Explains conditions and procedure for obtaining immunity from penalty and prosecution
- FAQs
- A closing chapter compiles frequently asked questions to address practical doubts, including references to recent rulings under the new penalty regime
The structure of the book is as follows:
- Two-part Format
- Part I (Chapters 1–12) – Detailed exposition of the penalty law, discussing definitions, interpretative principles, the burden of proof, and the scope of Section 270A, plus the interplay with older penalty provisions
- Part II (Chapters 13–48) – Multiple chapters supplying draft responses, step-by-step submissions, and arguments for various common (and uncommon) tax-addition scenarios—ranging from the disallowance of expenditure, capital gains misreporting, to differences in book profits
- Logical Flow & Cross-References
- Each chapter builds on the preceding discussions, with ample cross-references to sections, rules, and landmark judgments
- Appendices and notes help readers quickly locate relevant forms, statutory language, or case precedents
- Practice-Oriented Approach – The text consistently moves from theoretical exposition to how these principles operate in disputes, providing sample contentions that a professional could adapt to their case.
Details
- Binding : Paperback
- Publisher : Taxmann
- Author : D.C. Agrawal, Ajay Kumar Agrawal
- Edition : 2nd Edition 2025
- Language : English
- ISBN-10 : 9789364554862
- ISBN-13 : 9789364554862
| Language | English |
|---|---|
| Author | D.C Agrawal |
| Publisher | Taxmann |
Only logged in customers who have purchased this product may leave a review.
Related products
Commentary on Income Tax (Set of 2 Vols) | Ashok Saraf 2026
Navigate the sweeping changes of India's new direct tax regime with Bharat's Commentary on Income Tax (Set of 2 Volumes). Authored by Senior Advocate Dr. Ashok Saraf and CA Dr. Ayush Saraf, this 1st Edition (2026) provides an authoritative, section-by-section analysis of the newly enacted Income-tax Act 2025.
-
✔ Complete Statutory Transition: Exhaustive commentary on the new Income-tax Act 2025, amended by the Finance Act 2026.
-
✔ Corporate & Business Focus: Deep-dive analysis into the computation of business profits, depreciation, and capital gains.
-
✔ Expert Authorship: Blends decades of constitutional litigation experience with modern corporate accounting (Ind AS) expertise.
Taxmann’s GST on Works Contract & Other Construction/EPC Contracts by Sudipta Bhattacharjee
Taxmann's GST on Works Contract & Other Construction/EPC Contracts by Sudipta Bhattacharjee, Rishabh Prasad, Abhishek Garg - 12th Edition 2026. First, this Taxmann publication provides the exact text on engineering agreements. Specifically, the authors detail the strict rules for infrastructure taxation. Furthermore, this twelfth edition covers all fundamental 2026 legal updates perfectly.
Taxmann’s GST Annual Return & Reconciliation by Vivek Laddha
Taxmann's GST Annual Return & Reconciliation by Vivek Laddha - 8th Edition 2026. GST Annual Return & Reconciliation (8th Edition | 2026) is an all-inclusive professional handbook for preparing and filing GSTR-9 and GSTR-9C under India's GST regime. Updated as per Notification No. 13/2025-CT dated 17th September 2025, it offers a 360° integration of law, accounting, audit, and procedural practices, ensuring accuracy, compliance, and audit readiness. Authored by Adv. Vivek Laddha, Dr Shailendra Saxena, and CA. Pooja Patwari, the book features amendment-driven analysis, 30+ case studies, 50+ FAQs, and practical checklists, supported by detailed financial linkages and stepwise filing guidance. It stands as an indispensable reference for GST professionals, corporates, and academicians seeking structured, error-free annual compliance.


Taxmann’s Business Analytics by H.K. Dangi – 1st Edition 2024
Taxmann's Business Analytics by H.K. Dangi - 1st Edition 2024. This book underscores the pivotal role of data in the contemporary business landscape, blending theoretical knowledge with practical application to prepare students and professionals for data analysis and strategic implementation. It aligns with the UGCF 2022 syllabus under the National Education Policy of the University of Delhi. Covering a wide array of topics from data preparation to ethics in business analytics, it integrates tools like MS Excel, Tableau, and R for comprehensive learning in business analytics.

Reviews
There are no reviews yet.