
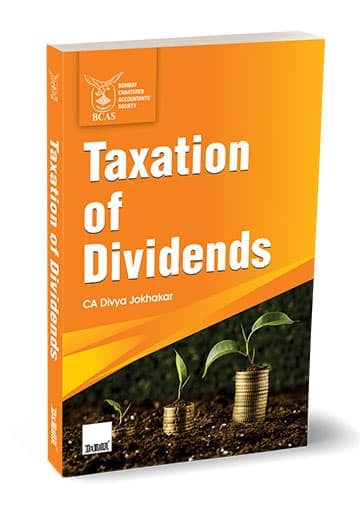
Taxmann’s Taxation of Dividends by BCAS – Edition 2026
₹385.00
Taxmann’s Taxation of Dividends by BCAS – Edition 2026. Taxation of Dividends offers a clear, authoritative, and practice-focused exposition of India’s dividend tax framework, tracing its evolution from the classical system to the DDT era and back to shareholder-level taxation after the Finance Act 2020. It provides comprehensive coverage of core provisions—including Section 2(22), Section 8, Section 80M, TDS rules, anti-avoidance measures, treaty implications, and the new regime taxing buybacks as dividends—supported by landmark case laws, CBDT circulars, illustrations, and FAQs. Designed for professionals and learners alike, the book equips readers with both conceptual clarity and practical guidance across compliance, planning, and litigation. It serves as an essential reference for tax practitioners, corporate finance teams, wealth managers, students, and policy researchers studying India’s evolving dividend tax landscape.
10 in stock
Taxmann’s Taxation of Dividends by BCAS – Edition 2026.
Taxmann’s Taxation of Dividends by BCAS – Edition 2026.
Description
Taxation of Dividends is a comprehensive and analytically rich reference that simplifies every aspect of dividend taxation under the Income Tax Act 1961. Published under the aegis of the Bombay Chartered Accountants’ Society (BCAS), the book traces the full journey of dividend taxation in India—from the classical regime to the Dividend Distribution Tax (DDT) era, and back to shareholder-level taxation post–Finance Act 2020. Built on a rigorous legislative, judicial, and administrative foundation, the book provides full-spectrum coverage of dividend-related provisions such as section 2(22) (including deemed dividends), section 8, section 80M, the erstwhile sections 115-O and 115BBDA, TDS provisions, anti-avoidance rules, DTAA implications, and the latest amendments affecting buybacks. Every topic is explained using case laws, examples, CBDT circulars, and chapter-wise FAQs to give readers conceptual clarity and practical application.
This book is designed as a definitive professional reference for:
- Chartered Accountants, Tax Consultants & Legal Practitioners dealing with dividend taxation, DDT legacy issues, TDS compliance, cross-border dividend withholding, and corporate tax planning
- Corporate Finance Teams, CFOs & Company Secretaries managing dividend declaration, inter-corporate dividends, buybacks, and compliance with sections 80M, 194, 195, and 206AA/206AB
- Wealth Managers, Investment Advisors & Portfolio Analysts who require clarity on the taxability of domestic and foreign dividends, treaty benefits, and characterisation issues
- Students & Academicians seeking a structured, authoritative textbook on dividend taxation backed by landmark judicial precedents and doctrinal interpretations
- Policy Researchers & Think Tanks studying the evolution of India’s dividend tax policy and its alignment with global anti-avoidance frameworks (MLI, PPT, GAAR)
The Present Publication is the 2026 Edition, authored by CA. Divya Jokhakar, commissioned by the BCAS and published by Taxmann. The noteworthy features of the book are as follows:
- [Historical & Policy Evolution] Explains the complete timeline of dividend taxation—1961 to 2025—including the introduction, amendments, and abolition of the DDT regime, and re-emergence of classical taxation from 1-4-2020
- [Deep Dive into Section 2(22)] Provides exhaustive coverage of the inclusive definition of dividends, including:
- Distributions out of accumulated profits
- Debentures, bonus shares to preference shareholders
- Liquidation and capital reduction distributions
- Deemed dividends under section 2(22)(e) with illustrations, judicial interpretations, exclusions, and grey areas highlighted by courts
- [Modern Issues | Buybacks Now Taxed as Dividend (Post–1 Oct 2024)] Explains the major shift introduced through section 2(22)(f), including classification, TDS, treaty issues, and different impacts for residents and non-residents
- [Characterisation, Head of Income & Deductibility] Discusses the subtle yet critical distinction between business income and income from other sources, and the limitations of deductions under section 57 post-Finance Act 2020
- [Tax Rates, Treaty Relief & MLI Framework] Compares domestic tax rates with DTAA rates, MFN clauses, beneficial ownership tests, and Principal Purpose Test (PPT) implications under the MLI regime
- [Case-Law Driven Analytical Approach] Contains an authoritative set of judicial precedents that shape dividend taxation
- [Practical FAQs] Includes more than 25 FAQs covering chargeability, TDS credit timing, dividend stripping, interest deductibility, NR filing requirements, and advance tax implications
The book is organised into eleven well-structured chapters, each covering a crucial domain of dividend taxation. Key areas include:
- Background and Developments till Date
- Economic role of dividends, interim vs. final dividends, and the double-taxation debate
- Detailed DDT chronology: rate movements, gross-up under section 115-O(1B), and introduction/withdrawal of section 115BBDA
- Definition of Dividend
- Text and commentary on section 2(22), including exclusions like loans in the ordinary course of money-lending business, earlier deemed dividends later set off, and demerger distributions
- Extended treatment of deemed dividend mechanics, substantial interest thresholds, “concern” concept, and the shareholder vs. concern debate in cases like Ankitech and National Travel Services.
- Section 8 – Year of Taxability
- Distinction between final and interim dividends; concept of ‘unconditionally made available’
- Case laws on conditional declarations, regulatory approvals and ineffective declarations (Mafatlal Gagalbhai, Pfizer)
- Dividends – Characterisation & Deductibility of Expenditure
- Trader vs. investor tests (CBDT Circulars 4/2007 and 6/2016)
- Detailed dissection of section 14A regime (now historical but relevant) and continuing controversies around identifying dividend-linked expenditure even after dividends became taxable
- Dividend – Impact of Status
- Domestic law position for each class of taxpayer with tabulated rates under 115AC, 115AD, 115E, 115A and IFSC concessions
- Treatment of foreign company recipients, deemed accrual under sections 5 and 9, and foreign tax credit with or without DTAA
- Dividend Stripping – Tax Aspects
- Worked numerical examples illustrating section 94(7) loss disallowance
- Linkage with AS-13 and the distinction between return on investment vs. return of investment
- Deduction u/s 80M
- Re-introduction background, numerical matrix of scenarios (no redistribution, partial redistribution, over-distribution)
- Discussion of interaction with section 148/148A proceedings
- Applicable Tax Rates & TDS on Dividends
- Comprehensive rate tables for residents and non-residents, surcharge/cess impact, MAT linkages, and special rates for ESOP GDRs
- Step-by-step explanation of TDS under sections 194, 194K, 195, 206AA, 206AB
- Judicial Precedents
- Digest-style summaries with facts, facts-issue-holding-takeaway format on DDT year of levy, Indo-Swiss treaty override on DDT rate, buyback valuation as colourable device, Oman dividend tax credit, section 14A scope and business-character of dividend income
- Frequently Asked Questions
- 12+ FAQs covering chargeability, deductions, head of income, timing vs. TDS credit, dividend stripping applicability, NR compliance and advance tax
- Buyback of Shares (Now Taxed as Dividend)
- Pre-2024 regime explained, followed by line-by-line analysis of new section 2(22)(f) and its cascading implications
The book follows a layered, issue-driven structure:
- Conceptual Introduction – Succinctly framing the problem (e.g. why deem certain payments as dividends, why restrict interest deductions, why re-introduce 80M)
- Statutory Text in Context – Key sections are quoted and then broken down into conditions, thresholds, explanations and provisos
- Judicial & Administrative Lens – Leading decisions and CBDT circulars are integrated into the narrative rather than relegated to footnotes, emphasising interpretative trends
- Illustrations & Tables – Especially in chapters on 94(7), 80M, tax rates and TDS, plus practical matrices for different investor categories
- Issues & Remarks/FAQs – Each chapter anticipates practical questions, grey areas and likely litigation triggers, and closes with clarificatory comments and open questions (for example, capitalisation of disallowed interest; treaty characterisation of buyback dividends).
Details
- Binding : Paperback
- Publisher : Taxmann
- Author : Bombay Chartered Accountants’ Society (BCAS)
- Edition : 2026
- Language : English
- ISBN-10 : 9789371267199
- ISBN-13 : 9789371267199
Only logged in customers who have purchased this product may leave a review.
Related products
Commentary on Income Tax (Set of 2 Vols) | Ashok Saraf 2026
Navigate the sweeping changes of India's new direct tax regime with Bharat's Commentary on Income Tax (Set of 2 Volumes). Authored by Senior Advocate Dr. Ashok Saraf and CA Dr. Ayush Saraf, this 1st Edition (2026) provides an authoritative, section-by-section analysis of the newly enacted Income-tax Act 2025.
-
✔ Complete Statutory Transition: Exhaustive commentary on the new Income-tax Act 2025, amended by the Finance Act 2026.
-
✔ Corporate & Business Focus: Deep-dive analysis into the computation of business profits, depreciation, and capital gains.
-
✔ Expert Authorship: Blends decades of constitutional litigation experience with modern corporate accounting (Ind AS) expertise.
Taxmann’s MSME Digest By Mukesh Mohan Gupta
Taxmann's MSME Digest By Mukesh Mohan Gupta - 1st Edition 2026. First, the MSME Digest serves as a comprehensive legal guide. Specifically, it consolidates the evolving laws governing India's Micro, Small, and Medium Enterprises (MSME) sector. Furthermore, this practice-ready reference brings together landmark decisions from the Supreme Court and various High Courts.
Taxmann’s GST Annual Return & Reconciliation by Vivek Laddha
Taxmann's GST Annual Return & Reconciliation by Vivek Laddha - 8th Edition 2026. GST Annual Return & Reconciliation (8th Edition | 2026) is an all-inclusive professional handbook for preparing and filing GSTR-9 and GSTR-9C under India's GST regime. Updated as per Notification No. 13/2025-CT dated 17th September 2025, it offers a 360° integration of law, accounting, audit, and procedural practices, ensuring accuracy, compliance, and audit readiness. Authored by Adv. Vivek Laddha, Dr Shailendra Saxena, and CA. Pooja Patwari, the book features amendment-driven analysis, 30+ case studies, 50+ FAQs, and practical checklists, supported by detailed financial linkages and stepwise filing guidance. It stands as an indispensable reference for GST professionals, corporates, and academicians seeking structured, error-free annual compliance.


Taxmann’s Business Analytics by H.K. Dangi – 1st Edition 2024
Taxmann's Business Analytics by H.K. Dangi - 1st Edition 2024. This book underscores the pivotal role of data in the contemporary business landscape, blending theoretical knowledge with practical application to prepare students and professionals for data analysis and strategic implementation. It aligns with the UGCF 2022 syllabus under the National Education Policy of the University of Delhi. Covering a wide array of topics from data preparation to ethics in business analytics, it integrates tools like MS Excel, Tableau, and R for comprehensive learning in business analytics.

Reviews
There are no reviews yet.