
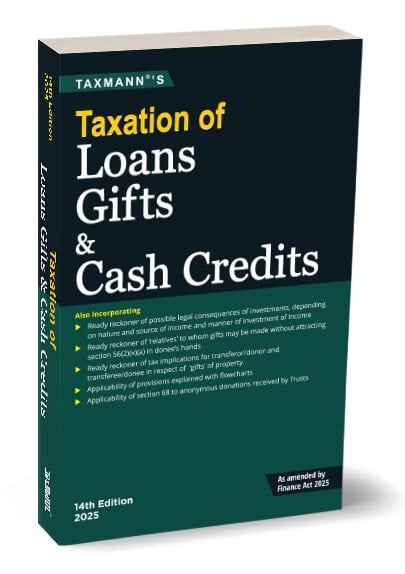
Taxmann’s Taxation of Loans Gifts & Cash Credits – 14th Edition 2025
Original price was: ₹1,650.00.₹1,320.00Current price is: ₹1,320.00.
Taxmann’s Taxation of Loans Gifts & Cash Credits As Amended by Finance Act, 2025 – 14th Edition 2025. The 14th edition comprehensively addresses legal provisions and practical issues related to unexplained cash credits, loans, deposits, and gifts under the Income-tax Act (Sections 68–69D), incorporating the latest Finance Act 2025 amendments. It also covers donee-based gift taxation under Section 56(2)(x), supported by illustrative examples, flowcharts, and ready reckoners. Divided into four parts—undisclosed income, gifts of money, gifts of immovable property, and gifts of movable property—it provides step-by-step guidance bolstered by case law. Featuring an alphabetical ready reckoner for quick reference, it is an indispensable resource for tax professionals, legal practitioners, corporate teams, and individuals. Detailed discussions on compliance, assessments, and defences make it ideal for resolving disputes and ensuring robust tax planning.
10 in stock
Taxmann’s Taxation of Loans Gifts & Cash Credits As Amended by Finance Act, 2025 – 14th Edition 2025.
Taxmann’s Taxation of Loans Gifts & Cash Credits As Amended by Finance Act, 2025 – 14th Edition 2025.
Description:
This book is a comprehensive and up-to-date treatise on the entire gamut of legal provisions and practical issues surrounding unexplained cash credits, loans, deposits, borrowings, and gifts under the Income-tax Act 1961. Meticulously revised to incorporate changes introduced by the Finance Act 2025, it explains the interplay of Sections 68 to 69D in detail, along with donee-based taxation of gifts under Section 56(2)(x). It incorporates illustrative examples, flowcharts, and handy-ready reckoners; this book provides a practical roadmap for understanding how various unexplained or undisclosed amounts are taxed—and how to ensure proper compliance or defend contentious cases before tax authorities.
This book is intended for the following audience:
- Chartered Accountants, Tax Practitioners, and Consultants – Looking for an in-depth analysis of the provisions dealing with unexplained income, loans, borrowings, gifts, and cash credits
- Advocates and Legal Professionals – Needing clarity on litigation aspects, interpretation of law, and precedent-based strategies for appeals and dispute resolution
- Corporate Finance and Compliance Teams – Seeking guidance on best practices for structuring transactions, raising capital, receiving gifts or loans, and fulfilling disclosure requirements under the Income-tax Act
- Individuals and HUFs – Needing clarity on personal transactions such as family gifts, undisclosed investments, or receipts from relatives and their tax implications
The Present Publication is the 14th Edition | 2025, amended by the Finance Act 2025. This book is authored by Taxmann’s Editorial Board with the following noteworthy features:
- [Comprehensive Guidance on Sections 68 to 69D] Explains the taxation of unexplained cash credits, investments, money, bullion, undisclosed expenditures, and hundi transactions
- [Donee-based Taxation of Gifts] Detailed coverage of Section 56(2)(x), including money gifts, immovable property, movable assets, artistic works, shares, and securities—complete with examples
- [Ready Reckoners] Instant reference tools listing out:
- Legal consequences of different types of ‘investments’ based on nature and source
- Who qualifies as a ‘relative’ for tax-free gifts
- Tax implications for both donor/transferor and donee/transferee in respect of property transfers
- [Flowcharts and Practical Scenarios] Step-by-step visual aids to clarify applicability, compliance requirements, and potential pitfalls under each section
- [Case Law and Illustrations] Judicial precedents and illustrative instances of additions, disallowances, and successful defences
- [Anonymous Donations and Trusts] Addresses the nuances of anonymous donations to charitable/religious trusts—how they intersect with Section 68 and Section 115BBC
- [Alphabetical Ready Reckoner] A quick index that alphabetically compiles topics like bogus purchases, penny stocks, share application money, demonetisation scenarios, etc., for immediate look-up
The coverage of the book is as follows:
- Division One – Undisclosed Income
- Chapters 1–18 comprehensively cover Sections 68 to 69D, exploring scenarios such as cash credits (including share capital, loans, and deposits), unexplained investments (lottery tickets, bullion, real estate), unexplained money (including demonetised currency), expenditures, and hundi transactions
- Detailed discussions on detection by the Department, voluntary disclosures, and how to defend assessments or additions made by AO
- Division Two – Donee-Based Taxation of Gifts of Money
- Chapters 19–25 analyse the entire framework under Section 56(2)(x) for taxing sums of money received as gifts, clarifying exemptions, relative definitions, monetary limits (the INR 50,000 threshold), and exceptions (like marriage or inheritance)
- Division Three – Taxation of Gifts of Immovable Property
- Chapters 26–32 discuss transactions involving land, buildings, or both—covering conditions for taxability, date of receipt, valuation (stamp duty value vs. consideration paid), partial consideration below fair market value, and capital gains consequences upon subsequent transfer
- Division Four – Taxation of Gifts of Movable Property
- Chapters 33–42 deal with movable assets (shares, securities, jewellery, bullion, artistic works), explaining fair market valuation rules, thresholds, and the interplay with Section 50CA, if applicable
- Appendices
- Appendix 1–4 incorporate relevant extracts of the Income-tax Act 1961, Income-tax Rules 1962, guidelines for jewellery seizure during the search, and relevant provisions of the Securities Contracts (Regulation) Act 1956, among others
- Alphabetical Ready Reckoner to Gifts, Loans & Cash Credits
- A user-friendly, A-to-Z index of typical issues, case references, practical scenarios, and cross-references to the relevant chapter paragraphs—making research quick and efficient
The structure of the book is as follows:
- The book is logically segmented into four major divisions based on the type of transaction or asset (undisclosed income, gifts of money, gifts of immovable property, and gifts of movable property)
- Each division is subdivided into chapters that provide a focused, in-depth exploration of specific issues—supported by examples, judicial rulings, flowcharts, and practice notes
- Key highlights or ‘ready reckoners’ appear at the start of each division and frequently within chapters, offering snapshots of rules, definitions, and immediate checklists.
Details
Only logged in customers who have purchased this product may leave a review.
Related products
Commercial’s Understanding of Provisions of Deemed Income by Ram Dutt Sharma
Master the complex legal fictions that turn undisclosed financial transactions into massive tax liabilities. Commercial's Understanding of Provisions of Deemed Income (1st Edition, 2026) is a highly focused reference manual authored by former Income Tax Officer Ram Dutt Sharma.
-
✔ The Finance Act 2026 Updates: Fully aligned with the Income Tax Act 2025, detailing the latest statutory treatments of income deemed to accrue or arise in India.
-
✔ Unexplained Wealth: Deep, operational analysis of deemed income arising from unexplained cash, investments, expenditure, and assets (Sections 68, 69, 69A-D).
-
✔ Insider Strategy: Written by a 35-year veteran of the Income Tax Department, providing unparalleled clarity for defending against scrutiny assessments and reassessments.
Commentary on Income Tax (Set of 2 Vols) | Ashok Saraf 2026
Navigate the sweeping changes of India's new direct tax regime with Bharat's Commentary on Income Tax (Set of 2 Volumes). Authored by Senior Advocate Dr. Ashok Saraf and CA Dr. Ayush Saraf, this 1st Edition (2026) provides an authoritative, section-by-section analysis of the newly enacted Income-tax Act 2025.
-
✔ Complete Statutory Transition: Exhaustive commentary on the new Income-tax Act 2025, amended by the Finance Act 2026.
-
✔ Corporate & Business Focus: Deep-dive analysis into the computation of business profits, depreciation, and capital gains.
-
✔ Expert Authorship: Blends decades of constitutional litigation experience with modern corporate accounting (Ind AS) expertise.
Bharat’s Law, Practice & Procedure of GST Appeals by Dr. J.K. Mittal
Bharat's Law, Practice & Procedure of GST Appeals by Dr. J.K. Mittal - 1st Edition 2026. First, this Bharat publication provides the exact, practice-ready text on indirect tax litigation and dispute resolution in India. Specifically, written by Dr. J.K. Mittal, this definitive legal reference manual details the strict rules of managing appeal files. Furthermore, this 1st edition completely incorporates all recent operational guidelines and structural tribunal mandates running smoothly through 2026.
Taxmann’s Tax Prosecution under Income-tax/GST & Black Money Laws by Gagan Kumar
Taxmann's Tax Prosecution under Income-tax/GST & Black Money Laws by Gagan Kumar - 5th Edition 2026. First, this Taxmann publication provides the exact text on criminal tax liabilities. Specifically, author Gagan Kumar details the strict rules for tax prosecution. Furthermore, this fifth edition covers all fundamental 2026 statutory frameworks perfectly.
Taxmann’s Direct Taxes Ready Reckoner by Vinod K Singhania
Taxmann's Direct Taxes Ready Reckoner by Vinod K Singhania - 50th Edition March 2026 (A.Y. 2026-27) & (Tax Year 2026-27). First, this Taxmann publication provides the exact tax rates. Specifically, author Vinod K Singhania details strict tax planning. Furthermore, this 50th Edition covers all fundamental assessment year updates perfectly.

Taxmann’s Business Analytics by H.K. Dangi – 1st Edition 2024
Taxmann's Business Analytics by H.K. Dangi - 1st Edition 2024. This book underscores the pivotal role of data in the contemporary business landscape, blending theoretical knowledge with practical application to prepare students and professionals for data analysis and strategic implementation. It aligns with the UGCF 2022 syllabus under the National Education Policy of the University of Delhi. Covering a wide array of topics from data preparation to ethics in business analytics, it integrates tools like MS Excel, Tableau, and R for comprehensive learning in business analytics.

Reviews
There are no reviews yet.