
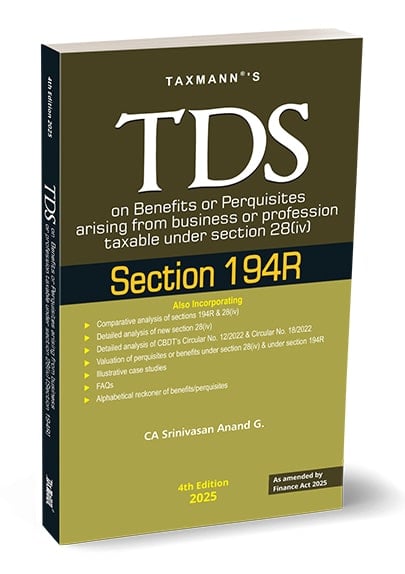
Taxmann’s TDS on Benefits or Perquisites under Section 194R by Srinivasan Anand G.
Original price was: ₹795.00.₹636.00Current price is: ₹636.00.
Taxmann’s TDS on Benefits or Perquisites under Section 194R by Srinivasan Anand G. – 4th Edition 2025. This 4th Edition commentary—authored by CA. Srinivasan Anand G., updated by the Finance Act 2025—provides an in-depth guide on TDS obligations for benefits or perquisites under Section 194R, in tandem with Section 28(iv). It clarifies valuation norms, thresholds, and exemptions supported by CBDT guidelines, illustrative case studies, and FAQs. Readers gain step-by-step insights on handling a range of scenarios—from free samples and loan waivers to brand ambassador gifts—while ensuring full compliance. Structured into foundational, advanced, and practical guidance chapters, plus an alphabetical reckoner, it is an indispensable reference for tax professionals, CFOs, and businesses.
10 in stock
Taxmann’s TDS on Benefits or Perquisites under Section 194R by Srinivasan Anand G. – 4th Edition 2025.
Taxmann’s TDS on Benefits or Perquisites under Section 194R by Srinivasan Anand G. – 4th Edition 2025.
Description
This book is a comprehensive and up-to-date commentary on the legal provisions governing the deduction of tax at source on benefits or perquisites in business or profession. It simplifies the scope of Section 194R alongside its interplay with Section 28(iv), incorporates key clarifications issued by the CBDT, and explains the valuation norms lucidly. It aims to guide readers on meeting TDS obligations for various benefits or perquisites—whether in cash, kind, or both.
This book is intended for the following audience:
- Chartered Accountants, Company Secretaries, and Lawyers who regularly advise on TDS and income-tax compliance issues
- CFOs, Finance Managers, and Accounts Teams who handle day-to-day TDS compliance within organizations and need clarity on Section 194R/28(iv)
- Tax Consultants and Advisers seeking in-depth analysis of evolving TDS rules on benefits or perquisites
- Business Owners & Startups to understand TDS implications on non-monetary benefits, free samples, promotional offers, etc.
The Present Publication is the 4th Edition | 2025, amended by the Finance Act 2025. This book is authored by CA. Srinivasan Anand G., with the following noteworthy features:
- [Comparative Analysis of Sections 194R & 28(iv)] Offers insights into how the two sections interrelate and clarify their respective scopes
- [Detailed Analysis of New Section 28(iv)] Explores the expanded definition of taxable benefits or perquisites under the Income-tax Act, especially in light of recent amendments
- [Analysis of CBDT Circulars] Explains crucial official clarifications on TDS obligations, valuation, and procedural aspects
- [Valuation Norms for Perquisites/Benefits] Guides readers on how to measure or determine the fair market value of benefits, whether they are capital assets, shares, gifts, discounts, waivers, or other forms
- [Illustrative Case Studies] Showcases practical scenarios such as free samples, foreign tours, gifts to brand ambassadors, loan waivers, etc., and explains TDS treatment under Section 194R
- [Exhaustive FAQs] Answers practical questions on applicability, compliance challenges, coverage, and possible pitfalls
- [Alphabetical Reckoner of Benefits/Perquisites] A ready reference for quick look-ups of various kinds of benefits/perquisites and their TDS implications
The coverage of the book is as follows:
- Conceptual Framework of Section 194R
- The rationale behind introducing TDS on benefits/perquisites
- Salient features and essential ingredients of Section 194R
- Scope & Interplay with Section 28(iv)
- A line-by-line analysis of the newly amended Section 28(iv)
- The distinction between ‘benefit/perquisite’ and ‘consideration’ or ‘compensation’
- Linking TDS with the chargeability under the ‘business or profession’ head of income
- Valuation Methodologies
- Step-by-step approach for items purchased, items manufactured, or intangible benefits
- Determining Fair Market Value of capital assets, shares, land, jewellery, etc.
- CBDT’s guidelines on purely monetary perquisites and combined (cash + kind) benefits
- Applicability and Exemptions
- Threshold limits (e.g., benefits valued at ₹20,000 or less)
- Special Scenarios – Discounts, rebates, cashback, OTS for loan waivers, interest-free loans
- Treatment of freebies to doctors, brand ambassadors, and social media influencers
- Compliance & Procedural Aspects
- Ensuring TDS deduction/payment when the benefit is in kind or partly in kind and partly in cash
- Removal of Difficulty Clause – Powers of CBDT to issue guidelines and the binding nature thereof.
- Consequences of Non-compliance – Penalties (Section 271C), prosecution (Section 276B), interest, etc.
- Illustrative Scenarios & Case Studies
- Application of TDS where share application money is written back, complimentary copies given to authors, foreign trips for distributors, gifts to brand ambassadors, etc.
- Specific coverage on free samples, reimbursement issues, disclaimers, and potential litigation avenues
- Alphabetical Reckoner
- An A-to-Z list of diverse benefits/perquisites (from amalgamation scenarios to tips collected by hotels) with cross-references to relevant paragraphs and chapters
The structure of the book is as follows:
- Introductory Chapters (1–5) – They establish the foundational concepts of Section 194R and define who must deduct TDS, who is the recipient, and what constitutes a benefit/perquisite
- Core Analytical Chapters (6–25) – These chapters go deeper into the scope, valuation, CBDT’s clarifications, and special scenarios—ranging from purely monetary benefits to various forms of non-monetary perquisites
- Advanced & Special Topics (26–35) – These chapters address intricate issues such as amalgamations, shareholder transactions, partner retirements, freebies for doctors, brand ambassadors, etc.
- Practical Guidance (Chapters 36–38) – These chapters wrap up common FAQs, potential litigation areas, and penalty/prosecution provisions, offering a holistic view of the entire framework.
Details
- Binding : Softcover
- Publisher : Taxmann
- Author : Srinivasan Anand G.
- Edition : 4th Edition 2025
- Language : English
- ISBN-10 : 9789364555524
- ISBN-13 : 9789364555524
| Publisher | Taxmann |
|---|---|
| Language | English |
| Author | Srinivasan Anand G |
Only logged in customers who have purchased this product may leave a review.
Related products
Commentary on Income Tax (Set of 2 Vols) | Ashok Saraf 2026
Navigate the sweeping changes of India's new direct tax regime with Bharat's Commentary on Income Tax (Set of 2 Volumes). Authored by Senior Advocate Dr. Ashok Saraf and CA Dr. Ayush Saraf, this 1st Edition (2026) provides an authoritative, section-by-section analysis of the newly enacted Income-tax Act 2025.
-
✔ Complete Statutory Transition: Exhaustive commentary on the new Income-tax Act 2025, amended by the Finance Act 2026.
-
✔ Corporate & Business Focus: Deep-dive analysis into the computation of business profits, depreciation, and capital gains.
-
✔ Expert Authorship: Blends decades of constitutional litigation experience with modern corporate accounting (Ind AS) expertise.
Bharat’s Law, Practice & Procedure of GST Appeals by Dr. J.K. Mittal
Bharat's Law, Practice & Procedure of GST Appeals by Dr. J.K. Mittal - 1st Edition 2026. First, this Bharat publication provides the exact, practice-ready text on indirect tax litigation and dispute resolution in India. Specifically, written by Dr. J.K. Mittal, this definitive legal reference manual details the strict rules of managing appeal files. Furthermore, this 1st edition completely incorporates all recent operational guidelines and structural tribunal mandates running smoothly through 2026.
Bharat’s Income Tax Act, 2025 (Pocket Edn.) – 39th Edition 2026
Bharat's Income Tax Act, 2025 (Pocket Edn.) - 39th Edition 2026. First, this Bharat publication provides the exact pocket-sized legal text on direct tax laws for professionals in India. Specifically, compiled by Bharat Law House, this compact reference book details the statutory rules of the newly active Income Tax Act, 2025. Furthermore, this 39th edition includes highly useful comments and cross-reference tables updated for easy use on the go.
Taxmann’s GST on Works Contract & Other Construction/EPC Contracts by Sudipta Bhattacharjee
Taxmann's GST on Works Contract & Other Construction/EPC Contracts by Sudipta Bhattacharjee, Rishabh Prasad, Abhishek Garg - 12th Edition 2026. First, this Taxmann publication provides the exact text on engineering agreements. Specifically, the authors detail the strict rules for infrastructure taxation. Furthermore, this twelfth edition covers all fundamental 2026 legal updates perfectly.
Bharat’s Company law Ready Reckoner (2 Vols) by Dr. D.K. Jain
Bharat's Company law Ready Reckoner (2 Volumes) by Dr. D.K. Jain - 28th Edition 2026. First, this Bharat publication provides a complete guide to company law. Specifically, it details the exact rules for corporate compliance perfectly. Furthermore, this 28th Edition 2026 covers all statutory amendments across two massive volumes.
Taxmann’s Income Tax Act – As Amended by Finance Act 2025
Taxmann's Income Tax Act - As Amended by Finance Act 2025 - 70th Edition 2025. This book seamlessly integrates all amendments from the Finance Act 2025 into a single authoritative text. It offers extensive annotations, cross-references, and legislative history, catering to practitioners, academics, and libraries. Separate divisions also cover the Finance Act 2025, STT, CTT, and the now-ended Equalisation Levy, ensuring a holistic overview of direct tax laws. A user-friendly layout—with marginal notes, footnotes, and a comprehensive subject index—enables efficient navigation. Backed by meticulous editorial accuracy, this volume remains a definitive guide to direct tax legislation.

Taxmann’s Guide to Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT) – 2nd Edition 2022
Taxmann's Guide to Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT) - 2nd Edition 2022. This book provides a comprehensive analysis of Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT). The analysis is done in light of the Income-tax Act 1961, Income-tax Rules 1962, and Relevant Case Laws. This book is amended by the Finance Act 2022.
Reviews
There are no reviews yet.