
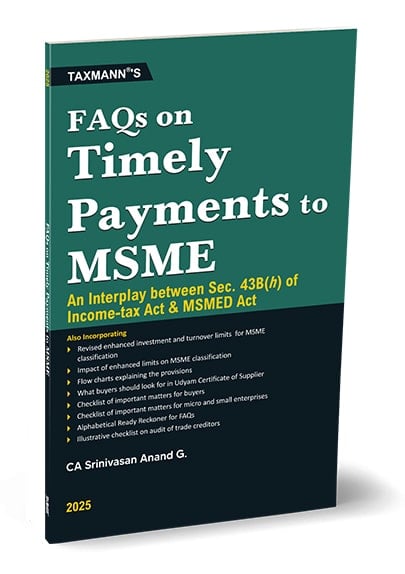
Taxmann’s FAQs on Timely Payments to MSME by Srinivasan Anand G
Original price was: ₹445.00.₹356.00Current price is: ₹356.00.
Taxmann’s FAQs on Timely Payments to MSME – An Interplay between Sec. 43B(h) of the Income-tax Act & MSMED Act by Srinivasan Anand G – Edition March 2025. This book explains how Section 43B(h) of the Income-tax Act converges with the MSMED Act to ensure timely payments to Micro and Small Enterprises (MSEs). It highlights the implications for buyers regarding disallowances, interest liabilities, and reporting requirements when payments exceed statutory deadlines. It incorporates FAQs, flowcharts, case studies, and checklists; the book offers straightforward guidance on complex practical scenarios. Aimed at professionals, businesses, and academics, it covers updated definitions, Udyam Registration norms, and best compliance and risk mitigation practices.
10 in stock
Taxmann’s FAQs on Timely Payments to MSME – An Interplay between Sec. 43B(h) of the Income-tax Act & MSMED Act by Srinivasan Anand G – Edition March 2025.
Taxmann’s FAQs on Timely Payments to MSME – An Interplay between Sec. 43B(h) of the Income-tax Act & MSMED Act by Srinivasan Anand G – Edition March 2025.
Description
This book is a specialised guide explaining how the newly introduced provisions under Section 43B(h) of the Income-tax Act affect payments to Micro and Small Enterprises (MSEs). It also discusses how these provisions converge with the long-standing requirements of the MSME Development Act, 2006 (MSMED Act), particularly on timely settlement of dues and the consequences of non-compliance. It aims to provide in-depth clarity on every significant question and challenge that could arise while interpreting or applying Section 43B(h), especially from the buyer’s perspective. It incorporates flowcharts, ready reckoners, illustrative case studies, and practical checklists.
This book is intended for the following audience:
- Chartered Accountants, Company Secretaries & Cost Accountants – For advising and auditing compliance with Section 43B(h) of the Income-tax Act, MSMED Act disclosures, and interest liabilities
- Tax Practitioners & Legal Professionals – For representing clients’ cases and ensuring adherence to statutory obligations under both tax laws and MSME provisions
- Finance & Accounting Teams, CFOs – For internal policy framing, guiding timely settlement of invoices from MSE suppliers, and mitigating disallowances under Section 43B(h)
- MSME Entrepreneurs & Business Owners – To understand the legal protections afforded to MSEs and the new compliance obligations imposed on their customers
- Students & Academicians – For a comprehensive understanding of emerging topics in tax and MSME legislation
The Present Publication is the 2025 Edition, authored by CA. Srinivasan Anand G. This book is amended upto 30th March 2025, with the following noteworthy features:
- [Comprehensive FAQs] Clear, succinct answers to frequently asked questions, covering everything from the definition of micro and small enterprises to complex issues of delayed payments and interest calculation
- [Flowcharts & Visual Aids] Easy-to-follow flowcharts outlining the compliance steps, especially highlighting the interplay between Section 43B(h) and the MSMED Act’s provisions on payment timelines
- [Ready Reckoner & Checklists]
- An alphabetical ready reckoner for quick reference to FAQs and crucial legal concepts
- Practical checklists for buyers to ensure foolproof compliance in dealing with MSE suppliers
- Dedicated checklists for micro and small enterprises, enabling them to safeguard their rights under the MSMED Act
- [Illustrative Audit Checklist] Specially designed checklist for auditing trade creditors, ensuring that auditors can efficiently spot and report potential disallowances under Section 43B(h)
- [Case Studies & Practical Scenarios] Examples illustrating the calculation of due dates, handling of delayed payments, and the interplay of interest liability under the MSMED Act and disallowance under Section 43B(h)
- [Updates on MSME Provisions] Covers the latest definitions, clarifications, and notifications under the MSMED Act, including Udyam Registration norms, classification criteria (investment and turnover), and allied documentation
- [Timely Topic] The book addresses a pressing need in the tax and business landscape post-introduction of Section 43B(h), ensuring stakeholders are well-informed of the newer compliance obligations and potential pitfalls
- [Focus on Practical Application] Written in plain language with ample examples, the content is not only theoretically grounded but also highly practice-oriented
- [Authoritative & Trusted] Authored by CA Srinivasan Anand G. and published by Taxmann, both known for their reliable and comprehensive coverage of tax and corporate laws
- [Essential for All Scales of Business] Whether an entity is a leading corporation or a medium-sized firm, timely payment compliance to MSMEs is now integral to avoiding disallowances and preserving goodwill
The coverage of the book is as follows:
- Legal Landscape & Background
- Objects and rationale behind Section 43B(h)
- Historical approach to MSME payment timelines and how Section 43B(h) augments the MSMED Act
- Applicability & Interpretation
- Detailed guidance on which buyers (companies, firms, charitable trusts, etc.) must comply with Section 43B(h)
- Nuanced explanations on whether unregistered MSEs fall under the purview of these provisions
- Payment Timelines & Disallowances
- Step-by-step walkthrough of payment due dates under Section 15 of the MSMED Act
- The chain of consequences when payments to MSE suppliers are delayed
- How to compute disallowances under Section 43B(h), and the circumstances for reversing these disallowances upon actual payment
- Interest Under Section 16 of the MSMED Act
- Clarification on interest liability triggered by late payments
- Intersection with disallowances under Section 23 of the MSMED Act
- Disclosure Requirements & Audit Concerns
- Mandatory disclosure of amounts due to MSEs in the buyer’s annual accounts under Section 22
- Comprehensive coverage on reporting requirements in the Tax Audit Report (Form No. 3CD) with particular emphasis on Clause 22
- Practical Ready Reckoners & Checklists
- Alphabetical reference for critical terms and concepts
- Buyer’s checklist to ensure compliance and avoid potential penal interest or disallowances
- Checklist for MSEs to leverage their legal safeguards
- Appendices & Reference Materials
- Relevant statutory provisions (excerpts from the Income-tax Act and the MSMED Act)
- Notifications, circulars, and office memoranda related to MSME registration, classification, and benefits
The structure of the book is as follows:
- Chapter-wise FAQs – Organised by thematic sections, each chapter deals with a distinct aspect of Section 43B(h) or the MSMED Act—such as definitions, applicability, interest liabilities, etc.
- Alphabetical Ready Reckoner – A quick index to jump to specific topics or commonly encountered queries
- Practical Insights Section – A separate elaboration focusing on practical scenarios, methods to identify MSE suppliers via Udyam Certification, and the critical do’s and don’ts in payment workflows
- Checklists & Flowcharts – Embedded within the chapters to guide readers through step-by-step compliance procedures and best practices
- Appendices – Consolidates statutory extracts, government notifications, and clarifications, making it a one-stop resource for legal reference
Details
- Binding : Paperback
- Publisher : Taxmann
- Author : Srinivasan Anand G
- Edition : March 2025
- Language : English
- ISBN-10 : 9789364559584
- ISBN-13 : 9789364559584
| Publisher | Taxmann |
|---|---|
| Language | English |
| Author | Srinivasan Anand G |
Only logged in customers who have purchased this product may leave a review.
Related products
Bharat’s Income Tax Act, 2025 (Pocket Edn.) – 39th Edition 2026
Bharat's Income Tax Act, 2025 (Pocket Edn.) - 39th Edition 2026. First, this Bharat publication provides the exact pocket-sized legal text on direct tax laws for professionals in India. Specifically, compiled by Bharat Law House, this compact reference book details the statutory rules of the newly active Income Tax Act, 2025. Furthermore, this 39th edition includes highly useful comments and cross-reference tables updated for easy use on the go.
Taxmann’s Tax Prosecution under Income-tax/GST & Black Money Laws by Gagan Kumar
Taxmann's Tax Prosecution under Income-tax/GST & Black Money Laws by Gagan Kumar - 5th Edition 2026. First, this Taxmann publication provides the exact text on criminal tax liabilities. Specifically, author Gagan Kumar details the strict rules for tax prosecution. Furthermore, this fifth edition covers all fundamental 2026 statutory frameworks perfectly.
Taxmann’s Direct Taxes Ready Reckoner by Vinod K Singhania
Taxmann's Direct Taxes Ready Reckoner by Vinod K Singhania - 50th Edition March 2026 (A.Y. 2026-27) & (Tax Year 2026-27). First, this Taxmann publication provides the exact tax rates. Specifically, author Vinod K Singhania details strict tax planning. Furthermore, this 50th Edition covers all fundamental assessment year updates perfectly.
Taxmann’s GST Annual Return & Reconciliation by Vivek Laddha
Taxmann's GST Annual Return & Reconciliation by Vivek Laddha - 8th Edition 2026. GST Annual Return & Reconciliation (8th Edition | 2026) is an all-inclusive professional handbook for preparing and filing GSTR-9 and GSTR-9C under India's GST regime. Updated as per Notification No. 13/2025-CT dated 17th September 2025, it offers a 360° integration of law, accounting, audit, and procedural practices, ensuring accuracy, compliance, and audit readiness. Authored by Adv. Vivek Laddha, Dr Shailendra Saxena, and CA. Pooja Patwari, the book features amendment-driven analysis, 30+ case studies, 50+ FAQs, and practical checklists, supported by detailed financial linkages and stepwise filing guidance. It stands as an indispensable reference for GST professionals, corporates, and academicians seeking structured, error-free annual compliance.
Taxmann’s Guide to Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT) – 2nd Edition 2022
Taxmann's Guide to Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT) - 2nd Edition 2022. This book provides a comprehensive analysis of Minimum Alternate Tax (MAT) & Alternate Minimum Tax (AMT). The analysis is done in light of the Income-tax Act 1961, Income-tax Rules 1962, and Relevant Case Laws. This book is amended by the Finance Act 2022.

Reviews
There are no reviews yet.